Free Consultation
 PCI-DSS Compliant
 GDPR Ready
 ISO 27001
 NDA Protected
 AI Services
 AI App Development
 Generative AI Development
 AI Chatbot Development
 AI Integration Services
 AI For Fintech
 AI Financial Assistant Solution
 AI Insurance Agent Development
 Tech Stack
 OpenAI / GPT-4
 Claude / Anthropic
 Gemini / Google AI
 Llama / Open Source
 LangChain / LlamaIndex
 Pinecone / Pgvector
 AWS / Azure AI


 Fintech Solution
 Core Fintech
 Fintech App Development
 Neobank App Development
 eWallet App Development
 Payment Integration
 Lending Software
 BNPL Solution
 BNPL App Development
 Insurance App
 Investment App Dev
 Wealth Management App
 Crypto & DeFi
 DeFi App Development
 Crypto Wallet Dev
 Crypto Exchange Dev
 Trading Platform Dev
 Payments
 Compliance
 RegTech App Dev
 Fraud Detection
 Lending Ecosystem
 P2P Lending Platform
 Mortgage Lending
 Engagement
 Outsourcing Dev


 Mobile Development
 Mobile App Dev
 iOS App Development
 Android App Development
 React Native
 Flutter Development
 Web Development
 Node.js Development
 React.js Development
 Angular Development
 PHP / Laravel
 App Services
 UI/UX Design
 App Maintenance
 By Stage
 MVP Development
 Industry Solutions
 Healthcare App Dev
 Education App Dev
 Travel App Dev
 Real Estate App Dev
 Logistics Software
 Social Media App


 Hire Mobile Developers
 Hire iPhone Developers
 Hire Android Developers
 Hire React Native Devs
 Hire Flutter Developers
 Hire Web Developers
 Hire Node.js Developers
 Hire Angular Developers
 Hire PHP Developers
 Hire Laravel Developers
 How It Works
 Pre-Vetted Developers
 Ready In 48 Hours
 NDA From Day One
 Replace Guarantee

 Company
 About Us
 Portfolio
 Case Studies
 Blog / Insights
 Careers
 Contact Us
 Recognition


 Offices


TL;DR
- A money transfer app is the interface; the harder half is the platform behind it: payment/banking integrations, a ledger, compliance checks, fraud controls, and reconciliation.
- Most products fall into five types: P2P, B2B, consumer-to-business, domestic, and international, each with a different compliance load and cost profile.
- Core features (KYC/KYB, transfer initiation, transaction history, 2FA) get you to launch; advanced features (multi-currency, fraud scoring, bulk payouts, API access) are what let the product scale.
- Architecture should be treated as six layers: frontend, backend, payment, ledger/account, compliance, and data/infrastructure, with the ledger and compliance layers doing the most differentiating work.
- US builders should plan for FinCEN/MSB registration and state-by-state money-transmitter licensing early; licensing timelines often run longer than the software build itself.
- Development cost typically runs from roughly $25,000 for a basic app to $200,000+ for an advanced multi-currency platform; timelines run roughly 3–4 months to 8–12 months.
- Both vary significantly by scope, integrations, and developer location; treat any number as a planning estimate, not a quote.
- Common monetization models: transaction fees, FX margins, subscriptions, business-account fees, API/platform fees, and interest on stored balances.
Building a money transfer app means creating a financial system, not only a mobile interface. Beyond the screens a user taps, the product demands a ledger that tracks every dollar moving through it, payment and banking connections that actually move the money, compliance checks that satisfy regulators and banking partners, and monitoring that catches fraud and failed transactions before they become customer or regulatory problems.
Most of the cost, timeline, and risk in a money-transfer project comes from such underlying systems, not the UI. A basic MVP with one payment method and a single geography is a very distinct build from a multi-currency platform with business accounts, layered fraud controls, and bulk payouts, and the two shouldn’t cost or take the same amount of time, even though both are technically “money transfer apps.”
Before starting development, clear up: what type of transfer product you are building (P2P, B2B, consumer-to-business, cross-border, and domestic), which users and geographies you are serving first, which payment and banking partners you will depend on, and what compliance obligations apply to your specific model. This guide walks through what the product needs to do, how it’s architected, what it typically costs, and takes to build, and how to evaluate a development partner.
What is a Money Transfer App?
A money transfer app allows people to send, receive, and manage money digitally through linked bank accounts, cards, or an in-app wallet – instead of visiting a bank branch or handling cash.
While a traditional bank transfer can take one to three business days to clear, money-transfer apps are created to process peer-to-peer payments, remittances, and bill payments far faster, often within seconds for domestic transfers. Wise, Venmo, and PayPal are widely known examples; each is built on a similar underlying architecture but serves a different segment and use case.
That’s the surface-level definition. What matters more for a business buyer is what suits underneath the app screens. A functioning money-transfer product needs:
- Customer accounts
- Funding sources and payment methods
- Beneficiaries
- Transaction processing logic
- Payment and banking integration
- A ledger
- Compliance checks
- Fraud controls and transaction monitoring
- Reconciliation
- Notifications
- Admin and operations tooling
The app is the interface; the platform is the system that makes transfers actually work. A development conversation that only covers screens and app-store submission is skipping the harder half of the project – the integrations, ledger, and compliance layer that determine whether the product is reliable at scale.
Types of Money Transfer Apps
The type of transfer product you build determines your target audience, compliance burden, development cost, and core feature set. Most products fall into one or more of the following categories.
| Type | What It Covers | Complexity | Typical Dev Cost* |
| P2P (Person-to-Person) | Individuals sending to individuals, splitting bills, repaying friends, sending to family | Low–Medium | $25,000 – $80,000 |
| B2B (Business-to-Business) | Payroll, invoice settlement, supplier payments between businesses | High | $80,000 – $200,000+ |
| Consumer-to-Business | Bill pay, merchant collection, marketplace payouts from individuals to businesses | Medium | $40,000 – $100,000 |
| Domestic Transfer | Transfers within a single country over rails like ACH | Low–Medium | Varies with feature set above |
| International Transfer | Cross-border transfers involving FX, multi-currency, and international rails | Very High | $100,000 – $200,000+ |
*Directional estimates for planning purposes only – see the cost section below for what drives these ranges.
- P2P is usually the lowest-friction entry point: apps like Cash App, Venmo, and Zelle fall here, and the compliance load (KYC plus AML transaction-limit monitoring) is comparatively lighter than other categories.
- Consumer-to-business transfers (sometimes called Bill-Pay systems and I2B (Invoice-to-Business / Procure-to-Pay platforms) need to reconcile against orders or invoices, not only move money peer-to-peer, and often add loyalty or scheduled-payment features to drive repeat use.
- B2B products – think Payoneer, Stripe, or Tipalti – handle larger transaction values and need stronger approval workflows, audit trails, and fraud detection given the amounts involved.
- Domestic-only products can depend on a narrow set of rails – ACH in the US and face a simpler compliance and settlement picture than multi-country products.
- International transfer introduces multi-currency handling, international rails, FX conversions, and cross-border compliance that goes well beyond a domestic build. Remitly, Wise, and WorldRemit are the well-known players here. If cross-border is the core of what you are building, not an occasional use case, deeper architecture, compliance considerations, and FX handling are covered in our dedicated guide to cross-border payment platform development. If you are specifically evaluating what it takes to build something like Wise, see cost to build an app like Wise; for a Remitly-style remittance product, see Remitly-like app development.
If you are unsure which type fits your business, a domestic P2P MVP is usually the fastest way to validate demand before expanding into cross-border or B2B functionality.
How Does a Money Transfer App Work?
From a product and engineering standpoint, a transfer moves through a consistent sequence of stages – though the exact steps vary by payment method, geography, transfer type, and banking partner.
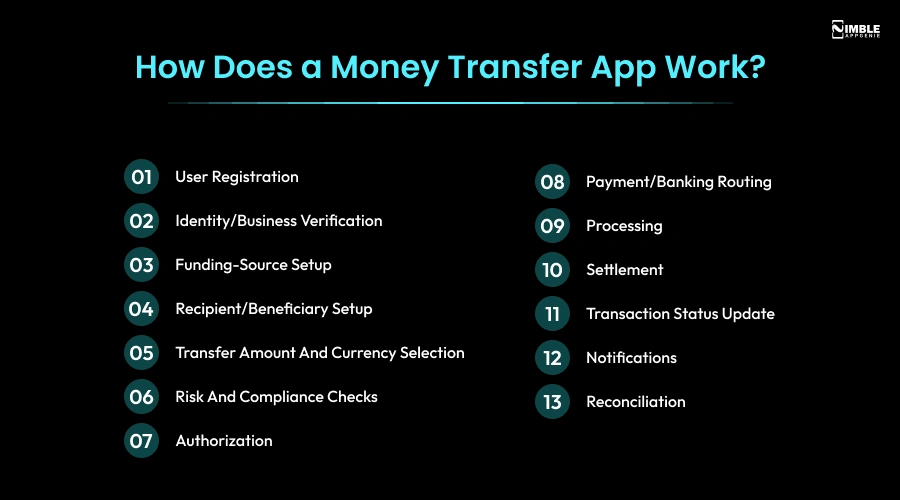
- User Registration: Account creation and initial identity capture.
- Identity/Business Verification: KYC for individuals, KYB for businesses
- Funding-Source Setup: Linking a bank account, wallet, or card.
- Recipient/Beneficiary Setup: Adding and verifying who receives the funds.
- Transfer amount and currency selection.
- Risk and Compliance Checks: Sanctions screening, AML rules, and fraud scoring.
- Authorization: The user confirms via PIN, a second factor, or biometrics, and the system confirms the transfer is approved to proceed.
- Payment/Banking Routing: Selecting the rail or provider that will move the funds.
- Processing: The actual movement of money through the chosen rail.
- Settlement: Funds finalizing between the relevant institutions.
- Transaction Status Update: Reflecting the current state to the user.
- Notifications: Informing the sender and recipient in real time.
- Reconciliation: Matching the internal record against provider and bank reports.
In practice, timing varies by rail: a domestic transfer might confirm in seconds and fully settle within hours, while a cross-border transfer can take one to two business days depending on the corridor and the receiving bank.
There’s no single universal flow – a business evaluating a development partner should expect that partner to map this sequence specifically for its chosen payment methods and geographies, not apply a generic template.
Core Features of a Money Transfer App
These are the features a regulated money-transfer app needs at launch. Missing any of them typically means regulatory review, failing app-store review, or basic user trust.
| Feature | What It Does | Business Value |
| Registration & KYC/KYB | Onboards users with identity verification, ID, selfie match, and address proof for individuals; business verification for KYB | Legal requirement in every regulated market; without it, you cannot legally process transactions |
| Bank/wallet linking | Connects funding sources via banking APIs or stores an in-app balance | Reduces dependency on real-time bank connectivity and improves speed |
| Transfer initiation (P2P) | Lets users send money via phone number, email, or account ID | Core product function; the reason people download the app |
| Payment gateway integration | Connects to processors (e.g., Stripe, Plaid, Razorpay) to execute the actual transfer | Without this, the app cannot move real money |
| Beneficiary management | Stores and verifies recipients, with saved-recipient shortcuts | Reduces friction on repeat transfers |
| Transaction history | Searchable log of past transfers, receipts, and failed attempts | Builds trust and satisfies AML audit-trail requirements |
| Multi-currency support | Handles multiple currencies with live exchange-rate conversion | Essential for any cross-border or remittance use case |
| Push notifications | Real-time alerts for success, failure, suspicious activity, low balance | Drives engagement and speeds up fraud response |
| MFA / 2FA | A second verification factor (OTP, biometric, authenticator) at login and transfer | Reduces account-takeover risk; a baseline expectation, not a differentiator |
| Multi-language support | Localizes the interface | Materially improves conversion in non-English markets |
| Admin dashboard | Internal visibility into users, transactions, and flags | Enables operations, support, and compliance oversight |
Advanced Features for a Scalable Money Transfer Platform
These are not needed at launch, but they are what separates a product that can scale from one that plateaus. Most teams plan these for version 2.0 and beyond.
| Feature | What It Does | Why It Matters |
| Fraud detection & risk scoring | Analyzes transaction patterns and device signals to flag suspicious activity in real time | Reduces losses and chargebacks; layered with rules-based checks rather than replacing them |
| Biometric authentication | Face or fingerprint verification for login and authorization | Faster and generally more resistant to credential theft than PIN-only flows |
| Scheduled & recurring transfers | Automatic transfers on a fixed schedule | High-value for payroll, remittances, and bill payments |
| Reconciliation tooling | Automated matching against provider and bank records | Becomes essential once transaction volume or provider count grows |
| Business accounts | Multi-user access, roles, and higher limits for company customers | Opens a B2B or consumer-to-business revenue line |
| Bulk payouts | Sending many payments in a single batch | Required for payroll or marketplace payout use cases |
| API access | Lets other businesses integrate with your transfer capability | Opens embedded-finance and platform-fee revenue models |
| RBAC | Role-based permissions for internal and business-user accounts | Limits exposure and supports compliance audits |
| Analytics | Operational and business reporting on transaction patterns | Surfaces where volume, risk, or friction is concentrated |
| Dispute management | Structured chargeback and dispute handling | Reduces resolution time and support overhead |
| Provider abstraction | Routes transfers across multiple providers without rebuilding integrations | Limits the damage from a single provider’s outage or policy change |
| Webhooks | Real-time event notifications to internal systems or business customers | Keeps downstream systems and partners in sync without polling |
What to Build First
Prioritizing everything at once is a common way to blow both budget and timeline. A practical phasing approach:
| Build Phase | Features to Include |
| MVP (v1.0) | Registration & KYC, wallet, P2P transfer, payment gateway, 2FA, push notifications, and transaction history |
| Version 2.0 | Multi-currency, fraud detection, biometric auth, in-app support, and scheduled transfers |
| Version 3.0+ | Predictive analytics, loyalty engine, smart suggestions, and automated compliance |
Biometric authentication and basic fraud detection are worth pulling into the MVP earlier than the rest of this list; they carry outsized weight for user trust and, in some markets, regulatory expectations.
Money Transfer App Architecture
A money-transfer product is a financial system with various interdependent layers, not a single application. Getting this right early determines how well the product scales under load, how quickly it can pass compliance audits, and how easily you can add features without rebuilding core infrastructure.
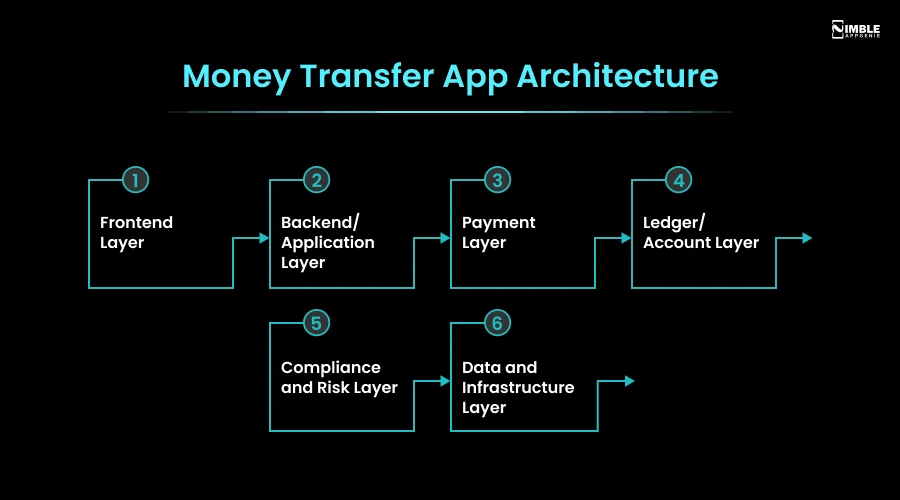
Frontend Layer
Android, iOS, and web – the transfer screen, notification center, onboarding flow, and transaction history the user actually touches. A well-built transfer flow completes in around 4 taps, with sub-2-second screen loads and accessibility that meets WCAG 2.1.
Backend/Application Layer
The engine that processes every request the frontend sends: validating a transfer, applying business rules, checking balances, and coordinating the other layers. API response times under roughly 300ms and horizontal scalability for transaction spikes are reasonable engineering targets here.
Payment Layer
Where money actually moves – banking APIs, payment processors, interbank settlement systems, and card networks. This layer should support multiple payment rails, retry logic on failed transfers, and real-time settlement status pushed back to the frontend.
Ledger/Account Layer
Balances, credits, debits, and transaction records – the financial sources of truth every other layer should be reconcilable against. This is distinct from general application data and deserves its own design attention; see the detailed section below.
Compliance and Risk Layer
KYC/KYB, AML rule monitoring, fraud scoring, and sanctions screening, wired into the transaction flow rather than run as a separate check at signup only. Automated KYC decisions in well-built systems typically resolve in well under a minute, with transactions screened against sanctions lists in real time and compliance reports exportable on demand.
Data and Infrastructure Layer
Databases, logging, cloud hosting, backups, monitoring, and observability. For a money-transfer product, data integrity is non-negotiable – every transaction should be recorded accurately and immutably enough to survive a regulatory audit or dispute, with data residency handled per jurisdiction where required.
How the Layers Work Together
Here’s a $500 international transfer traced across the stack:
| Step | Layer | What Happens |
| 1 | Frontend | User enters amount and recipient, taps “Send” |
| 2 | Backend | Request validated, balance checked, transfer rules applied |
| 3 | Compliance | AML check run, transaction screened against sanctions lists |
| 4 | Ledger | Transaction provisionally recorded as pending; debit and credit legs created |
| 5 | Payment | Banking API called, funds debited, transfer initiated to the recipient’s bank |
| 6 | Ledger/Data | Transaction marked complete on settlement confirmation, balances updated, notification triggered. |
Domestic transfers typically confirm within seconds to a few hours; cross-border transfers can take up to 48 hours depending on the receiving bank’s settlement cycle. A weakness in any single layer – a ledger that can’t handle partial failures, or compliance checks not wired into every transaction path creates risk for the whole system, not just that layer.
Payment and Banking Integrations
The integrations you connect determine what the product can actually do. Key categories:
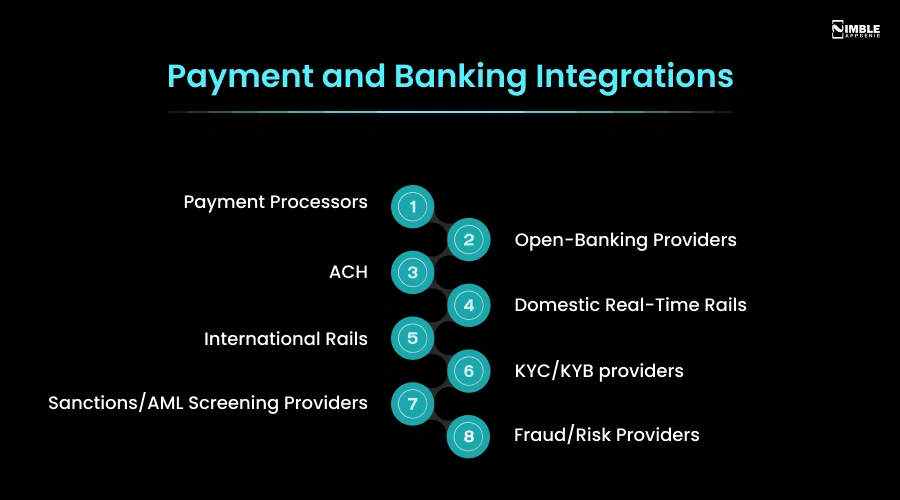
- Payment Processors (like Razorpay and Stripe): Handle card and some bank-based transactions.
- Open-Banking Providers: Enable account linking and identity/balance verification.
- ACH: The primary US rail for bank-to-bank domestic transfers.
- Domestic Real-Time Rails: Such as FedNow in the US, Faster Payments in the UK, or UPI in India, where relevant to your markets.
- International Rails: SWIFT and correspondent banking for cross-border settlement.
- KYC/KYB providers (like Jumio, Onfido, Sumsub): Automate identity and business verification.
- Sanctions/AML Screening Providers (like ComplyAdvantage, Refinitiv): Check senders and recipients against watchlists.
- Fraud/Risk Providers: Supply scoring, behavioral signals, and device intelligence.
Integration choices affect geographic coverage, cost, settlement speed, reliability, compliance posture, customer experience, and time to market. A provider with broad coverage but slower settlement is a different trade-off than one with narrower coverage but instant payouts – no single provider is right for every product. If you are building specifically for the UPI ecosystem, our UPI payment app development guide covers that rail in depth.
Ledger, Reconciliation & Transaction Management
Here, a money-transfer product succeeds or struggles operationally, and it’s the section that separates genuine fintech engineering from a standard app build.
Ledger
A ledger is the authoritative record of every financial movement in the system. Without one, a business can’t confidently answer “what is this user’s balance?” or “did this transfer actually complete?”
Most financially sound systems use double-entry principles: every transaction records both where money came from and where it went, so the books always balance.
In plain terms – if $100 leaves a sender’s funding source, the ledger records both the debit from the sender and the corresponding credit to the recipient (or a holding account), so nothing simply disappears or appears from nowhere in the records.
Transaction States and Idempotency
A transfer typically moves through defined states: Initiated, Pending, Authorized, Processing, Completed, Reversed, Failed, and Refunded. The exact set relies on the product and providers involved, but every transaction needs a clear, auditable state at every point in time – including when something goes wrong.
Idempotency matters here in a very practical way: if a network hiccup causes a client to submit the same “send $500” request twice, the system needs to recognize the duplicate and process it once, not twice. Without idempotent request handling, retries and timeouts – which are routine in any distributed payment system – can silently duplicate transfers.
Reconciliation
Reconciliation is the process of matching internal transaction records against what payment providers, settlement reports, and banks actually show. It catches discrepancies – a transfer marked complete internally that a provider reports as failed, or a settlement amount that doesn’t match expectations.
Reconciliation matters more as transaction volume and provider count grow. A product on one provider processing a few hundred transfers a month can often reconcile manually. A product on several providers processing thousands of transfers a day needs automated reconciliation, or discrepancies become expensive and slow to find.
Security Requirements for a Money Transfer App
No system is completely secure, and a development partner claiming “100% security” should be suspected. A well-built money-transfer product reduces risk systematically across layers:
- Tokenization of sensitive payment details so raw card or account data isn’t stored directly
- Encryption in transit and at rest (AES-256, TLS 1.3 are common baselines)
- MFA/biometrics for login and transaction authorization
- RBAC limiting what internal users and business accounts can see or do
- OAuth 2.0 and JWT-based secure API design: authenticated, rate-limited, validated endpoints
- Session security: appropriate timeouts and token handling
- Audit logs covering who did what, and when, across the system
- Fraud controls integrated into the transaction flow, not bolted on afterward
- Monitoring for unusual access patterns or system behavior
- Failure handling that fails safely, for example, not double-processing a transfer on a timeout
These measures reduce risk; they don’t eliminate it. Independent penetration testing against a recognized benchmark such as the OWASP Top 10 is a reasonable way to validate the approach rather than take it on faith.
KYC, KYB, AML & Regulatory Requirements
Regulatory obligations rely on the business model, the geographies served, the services offered, and the banking or payment partners involved. This section is general information, not legal advice – assess your specific obligations with qualified legal and compliance professionals.
Licenses and Frameworks That Commonly Apply
- MSB/MTL (Money Services Business / Money Transmitter License): In the US, most businesses that transmit funds need to register with FinCEN at the federal level and then obtain individual Money Transmitter Licenses in the states where their users reside – nearly every state requires one. New York’s BitLicense is widely regarded as the strictest. Multi-state licensing is a lengthy process – commonly many months, sometimes well over a year and should begin well before development finishes, not after.
- EMI License (Electronic Money Institution): Relevant mainly in the UK/EU; required if your platform lets users store funds in an integrated digital wallet rather than just pass funds through.
- PCI DSS: The standard for protecting card data. Applicable wherever the product handles card payment details.
- AML & KYC/KYB: Programs and monitoring designed to detect and report suspicious activity and to verify who you’re transacting with, both individuals (KYC) and businesses (KYB). Regulators treat online platforms as a plausible avenue for money laundering, so demonstrating a working AML/KYC program matters for licensing and for banking-partner relationships.
- GDPR & CCPA: Europe’s GDPR and California’s CCPA both require encrypting user data (AES-256 is a common baseline) and, for GDPR specifically, can require storing data within the relevant jurisdiction.
If Full Licensing Is Not Feasible Yet
Note: If you find obtaining licenses upfront not feasible because of cost, time, or market uncertainty, you can consider partnering with a Banking-as-a-Service (BaaS) provider. BaaS platforms, such as Treezor, Railsbank, or Synapse Finance, permit you to operate under their existing regulatory licenses as a white-label solution, notably diminishing your time to market. This is acknowledged as a common approach for early-stage fintech startups, where they launch under a BaaS umbrella, validate their product with real users, and apply for their licenses once they have transaction volume and investors, supporting cost justification.
How to Build a Money Transfer App?
The practical sequence below showcases both the product decisions and the compliance/technical work that should take place, roughly in this order.
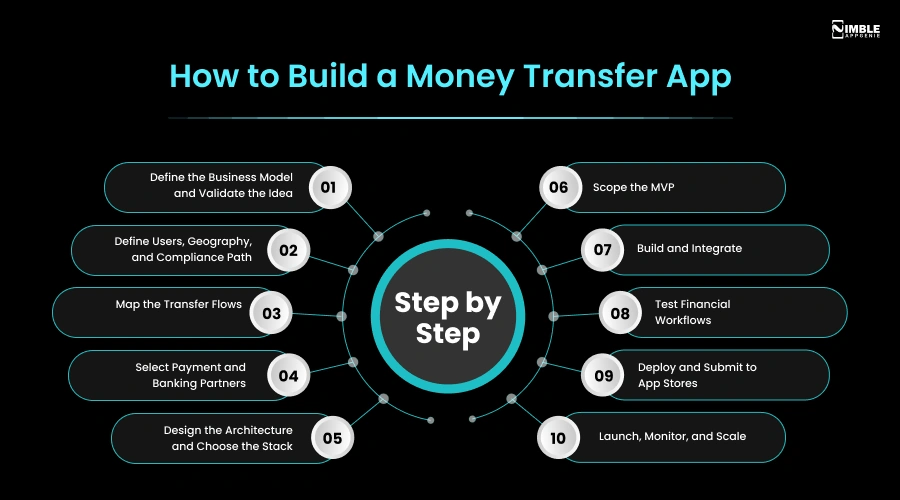
Step 1: Define the Business Model and Validate the Idea
Clarify who your primary user is (businesses, individuals, or both), which geography or payment corridor you are targeting, and what your core differentiator is – faster settlement, lower fees, an underserved audience, and better UX. The money-transfer market is competitive; winning products typically solve one issue better than PayPal or Wise, rather than being a generic alternative to either.
Step 2: Define Users, Geography, and Compliance Path
Your app type – B2B, P2P, domestic, consumer-to-business, or international – determines your compliance needs before development starts, not after. If you are planning a domestic P2P app in the US, MTL applications should start early given how long multi-state licensing can take.
If you are going cross-border, identify which corridors you will support at launch and research each one’s regulatory requirements. If speed to market matters more than owning your own license from day one, a BaaS partnership is worth evaluating.
Step 3: Map the Transfer Flows
Document funding, settlement, routing, reversals, failures, notifications, and refunds for each supported transfer type before writing code.
Step 4: Select Payment and Banking Partners
Evaluate candidates on geographic coverage, capabilities, reliability, fees, settlement speed, API quality, and onboarding requirements.
Step 5: Design the Architecture and Choose the Stack
Define the application, ledger, payment, infrastructure, and compliance layers and how they interact (see the architecture section above), and lock in the technology choices covered in the stack table below.
Step 6: Scope the MVP
A money-transfer MVP generally includes registration and KYC, one transfer method (domestic P2P is the simplest starting point), basic transaction history, 2FA, and push notifications. The MVP serves three purposes: it gets real user feedback before you build features nobody uses, it offers investors something concrete to evaluate, and it offers your compliance team a working product to test against regulatory requirements.
Step 7: Build and Integrate
Develop the core product and integrate the selected payment, identity, and compliance providers. A CI/CD pipeline that tests every commit before it merges is standard practice for a codebase handling real money.
Step 8: Test Financial Workflows
| Test Type | What It Covers |
| Functional testing | Every feature works as specified |
| Security testing | Penetration testing, OWASP Top 10 vulnerabilities |
| Performance testing | App handles peak transaction load without degradation |
| Compliance testing | KYC flows, AML triggers, and data storage meet regulatory requirements |
| Payment testing | All transaction types succeed, fail gracefully, and reconcile correctly |
| Device testing | App performs consistently across iOS and Android versions and screen sizes |
This should also cover specific failed transactions, pending transfers, refunds, reversals, provider errors, and duplicate requests – the edge cases that matter most in a financial product.
Step 9: Deploy and Submit to App Stores
Fintech apps generally face more scrutiny than average during submission. Google Play generally needs a Financial Services declaration and a compliant, publicly accessible privacy policy with transparent fee disclosure. A specialist team handles Apple’s review for financial apps and commonly takes longer than a typical app review; unclear fee disclosure, a missing KYC flow, or an insufficient privacy policy are common rejection reasons. Review timelines shift over time, so confirm current expectations with each platform directly rather than planning around a fixed number of days.
Step 10: Launch, Monitor, and Scale
Launch with monitoring in place from day one – crash and error tracking, a rollback plan, and real-time transaction monitoring if a critical payment bug surfaces. Treat the post-launch period as an ongoing operational responsibility, covered in more detail further down.
Build vs. Buy: What Should You Develop In-House?
Most money-transfer products mix custom-built components and third-party integrations, not one or the other.
Custom development usually makes sense for user experience and product-specific workflows, business rules unique to your product, operations systems, admin, and reporting tailored to your business, and anything that differentiates your platform from competitors.
The right balance depends on budget, time to market, target geography, regulatory complexity, expected scale, and how much differentiation matters to your business model. Building everything in-house is rarely the right answer; even well-funded fintech companies lean heavily on specialized third-party infrastructure for compliance and payment execution, reserving custom engineering for what actually differentiates them.
Technology Stack for a Money Transfer App
| Layer | Common Options |
| iOS | Swift, SwiftUI |
| Android | Kotlin |
| Cross-platform | React Native, Flutter |
| Backend | Node.js, Python (Django), Java (Spring Boot), Go |
| Database | PostgreSQL, MySQL, MongoDB (for flexible user data) |
| Payment APIs | Stripe, Plaid, Razorpay, SWIFT, depending on geography |
| KYC/AML | Jumio, Onfido, Sumsub, ComplyAdvantage |
| Cloud infrastructure | AWS, Google Cloud, Microsoft Azure |
| Security | AES-256, TLS 1.3, OAuth 2.0, JWT |
No single stack is universally “best.” The right choice depends on your product requirements, the integrations you need, expected scale, your team’s existing capabilities, and how quickly you need to move.
How Much Does It Cost to Build a Money Transfer App?
Costs below are estimated ranges, not fixed prices. Actual cost depends on your specific scope, integrations, and compliance requirements. Get a scoped quote before committing to a budget.
By Complexity
| Complexity Level | Estimated Range | Typical Scope |
| Basic App | $25,000 – $60,000 | Single geography, one transfer method, core KYC/AML, basic admin tools |
| Medium App | $60,000 – $120,000 | Multiple payment methods, stronger fraud controls, more complete reconciliation |
| Advanced App | $120,000 – $200,000+ | Multi-currency, multiple geographies, bulk payouts, API access, advanced fraud/compliance |
By Developer Location
Where your development team is based has a significant effect on total cost, independent of feature scope:
| Location | Typical Hourly Rate (USD) |
| United States (Tier 1 cities) | $100 – $250 |
| United States (Tier 2 cities) | $70 – $150 |
| Western Europe | $70 – $130 |
| Eastern Europe | $45 – $100 |
| South America | $35 – $75 |
| South Asia (e.g., India) | $25 – $70 |
| Southeast Asia (e.g., Philippines) | $25 – $60 |
| Africa | $20 – $45 |
How Tooling Choices Shift the Number
| Choice | Effect |
| Cross-platform frameworks (React Native, Flutter) | Can meaningfully cut development time versus separate native builds |
| Pre-built APIs/SDKs | Speeds up third-party integration versus building from scratch |
| Cloud infrastructure | Lowers upfront server cost but adds ongoing hosting fees |
| Open-source libraries | Reduces build time at no license cost |
| Machine learning/AI features | Adds meaningful cost and requires specialized expertise; include only with a concrete use case |
| Blockchain integration | Adds considerable cost and complexity relevant mainly for specific cross-border or settlement use cases |
| Advanced security/compliance tooling | Adds cost but reduces downstream regulatory and breach risk |
Most third-party integrations also carry ongoing per-transaction or monthly fees on top of the development cost; factor these into your operating budget, not just your build budget.
How Long Does It Take to Build a Money Transfer App?
| App Complexity | Typical Development Time |
| Basic P2P app | 3 – 4 months |
| Medium-complexity app | 5 – 7 months |
| Advanced, multi-currency/cross-border app | 8 – 12 months |
The best decision is to separate the two different timelines. Your software development timeline covers discovery, design, architecture, build, integration, and testing – the phases above.
Your external dependency timeline covers payment-provider onboarding, banking partnerships, app-store review, and licensing and compliance reviews, and these are largely out of a development partner’s control/
In particular, state money-transmitter licensing can run beyond the software build itself. No development partner can promise a universal delivery date without knowing your specific scope, regulatory path, and providers.
How Do Money Transfer Apps Make Money?
Most fintech platforms combine transaction-based revenue with one or more supplementary models:
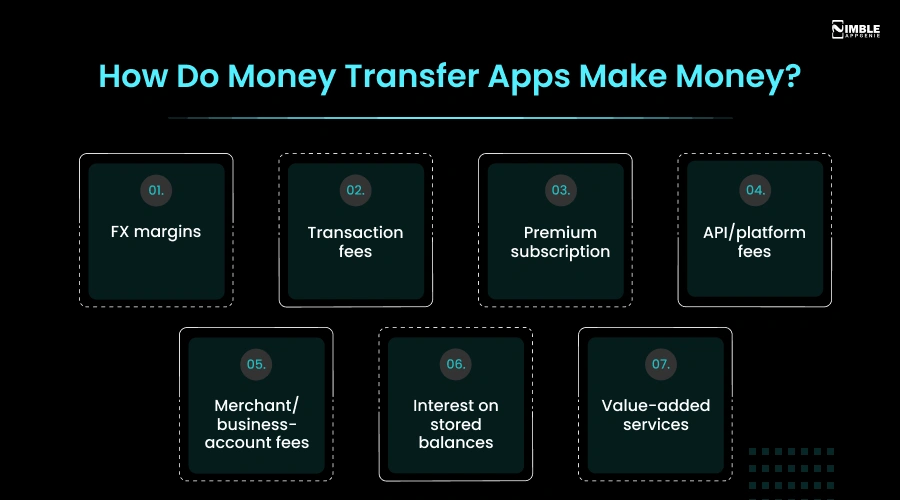
- FX margins: Earnings from the exchange-rate spread on cross-border transfers, rather than a separate fee.
- Transaction fees: A flat fee or percentage per transfer (a long-standing common benchmark for card transactions is around 2.9% + $0.30).
- Premium subscriptions: A monthly fee for higher limits, fee-free currency exchange, or faster transfers.
- API/platform fees: Charging other businesses per call or per integration for access to your transfer infrastructure.
- Merchant/business-account fees: Charging companies for payment processing or multi-user account access.
- Interest on stored balances: For products that hold user funds in a wallet, placing that float in interest-bearing accounts
- Value-added services: Adjacent offerings such as bill pay or budgeting tools
The right blend depends on your expected volume, customer segment, competitive pricing pressure, target geography, and your own provider costs. A low-margin, high-volume consumer product needs a very distinct pricing structure from a lower-volume B2B platform with higher transaction values. (If Zelle’s specific monetization approach is what you are researching, see our breakdown of how Zelle makes money.
Common Challenges in Money Transfer App Development
Most of these problems are manageable with the right architecture; the goal is to reduce their impact, not pretend they won’t happen.
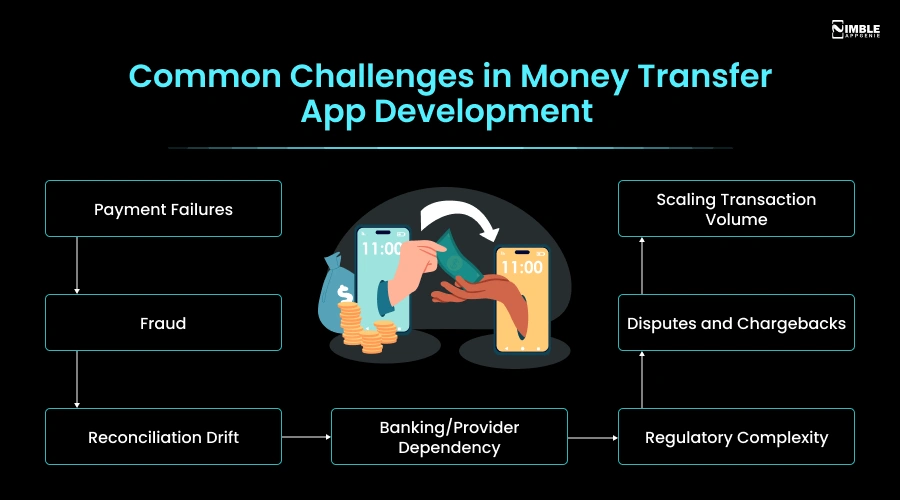
- Payment Failures: By clear transaction-state handling and automatic retry logic, not silent failure.
- Fraud: By layered controls (identity, verification, transaction scoring, ongoing monitoring) rather than a single checkpoint.
- Reconciliation Drift: By automated reconciliation as soon as volume or provider count increases beyond what manual matching can handle.
- Banking/Provider Dependency: By provider abstraction so a single outage or policy change doesn’t take down the whole product.
- Regulatory Complexity: By scoping your compliance path (Step 2 above) before development, not after.
- Disputes and Chargebacks: By structured dispute-management tooling and clear evidence trails.
- Scaling Transaction Volume: By load testing and horizontal scalability built in from the backend layer up.
What Happens After Launch?
While you start your product’s operational life, you launch the MVP. In the first 48 hours, you actively monitor crash reports and app errors, watch real-time transaction alerts, and have a rollback plan ready if a critical payment bug surfaces. Beyond that initial window, ongoing work typically includes:
- Applying security updates and maintaining provider integrations as their APIs evolve
- Monitoring system health and transaction success rates
- Keeping compliance processes current as regulations or partner requirements change
- Optimizing performance as volume grows
- Tuning fraud rules as new patterns emerge
- Adding new payment methods or geographies
- Supporting customers and resolving disputes
- Maintaining reconciliation accuracy as provider count and volume increase
- Producing operational and compliance reporting
A money-transfer product that is not actively maintained tends to accumulate risk quietly in reconciliation drift, outdated fraud rules, or compliance gaps until it surfaces as a real problem.
How to Choose a Money Transfer App Development Company
Evaluate potential partners on whether they have real experience with:
- Payment integrations across multiple providers and banking API connectivity
- Fintech products specifically, not just general app development
- Ledger and accounting system design
- Compliance-aware engineering – KYC/KYB, AML, sanctions screening
- Fraud and risk control implementation
- Reconciliation processes and financial edge-case testing
Useful questions to ask directly:
- What similar fintech products have you built?
- How would you architect the ledger for our model?
- How do you handle failed, reversed, or duplicate transactions?
- How do you approach reconciliation as provider count grows?
- What is your testing process for financial edge cases?
- What post-launch support do you provide?
A generic answer to these or an inability to speak specifically about reconciliation, ledgers, or transaction states signals the partner may be treating this as a standard app project rather than a financial system.
Why Choose Nimble AppGenie for Money Transfer App Development?
Since 2017, Nimble AppGenie has delivered 350+ completed projects across Android, iOS, and web, with dedicated fintech experience spanning eWallets, lending, neobanking, and payment platforms.
Our approach treats the ledger, compliance layer, and provider integrations as core engineering work from day one, not features bolted on late, because a money-transfer product that looks right but can’t reliably account for every dollar is not ready to launch.
Case Study: PayByCheck – Multi-Currency eWallet App
Challenge: The client needed a multi-currency eWallet platform working across Android, iOS, and web, with real-time currency exchange, KYC onboarding, secure fund transfers, and compliance across multiple regions. The core technical hurdles were robust transaction security, reliable currency exchange functionality, and an interface that worked for a diverse international user base.
What we built: A multi-currency wallet supporting fund addition, transfer, and exchange; Swift (iOS) and a PHP backend; a streamlined KYC onboarding flow for fast, compliant verification; a commission and limit management system for platform-level control; and a consistent cross-platform experience.
Delivered: A 5-person team, on a 3-month timeline. Full case study here.
If you are planning a money transfer app or platform, we can walk through your specific model, compliance requirements, and geography to help you scope the project accurately.
FAQs
Costs generally range from around $25,000 for a basic app to $200,000 or more for an advanced, multi-currency platform, depending on features, integrations, geographic coverage, and compliance requirements. Developer location also has a significant effect on total cost. These are directional estimates; get a scoped quote for your specific requirements.
A basic P2P app typically takes 3–4 months, a medium-complexity app 5–7 months, and an advanced multi-currency or cross-border platform 8–12 months. External dependencies – banking partnerships, provider onboarding, and licensing can extend the overall timeline well beyond the engineering work itself.
At minimum: registration and KYC/KYB, funding-source and payment-method support, transfer initiation, beneficiary management, transaction history, 2FA, and push notifications. Scalable platforms add multi-currency support, fraud detection, biometric authentication, business accounts, bulk payouts, and API access.
Requirements vary by business model and geography but commonly include KYC/KYB, AML programs, sanctions screening, PCI DSS where card data is involved, and in the US, FinCEN registration and state money-transmitter licensing. This isn’t legal advice; assess your specific obligations with qualified professionals.
Common models include transaction fees, FX margins on cross-border transfers, premium subscriptions, merchant or business-account fees, API/platform fees, and interest on stored wallet balances, with the right mix depending on customer segment and volume.
Yes, international transfers can be one transfer type within a broader product, though it introduces multi-currency handling, FX, and cross-border compliance requirements. For products where cross-border is the primary focus, see our guide to cross-border payment platform development.
Through layered controls: identity verification at onboarding, transaction-level risk scoring, ongoing transaction monitoring, sanctions screening, and audit logging, combined with human review for flagged activity. No system prevents fraud entirely, but layered controls reduce both frequency and impact.
Evaluate real fintech experience: ledger design, reconciliation, payment and banking integrations, compliance-aware engineering, and post-launch support, not just general app-development capability.
Niketan Sharma, CTO, Nimble AppGenie, is a tech enthusiast with more than a decade of experience in delivering high-value solutions that allow a brand to penetrate the market easily. With a strong hold on mobile app development, he is actively working to help businesses identify the potential of digital transformation by sharing insightful statistics, guides & blogs.