Free Consultation
 PCI-DSS Compliant
 GDPR Ready
 ISO 27001
 NDA Protected
 AI Services
 AI App Development
 Generative AI Development
 AI Chatbot Development
 AI Integration Services
 AI For Fintech
 AI Financial Assistant Solution
 AI Insurance Agent Development
 Tech Stack
 OpenAI / GPT-4
 Claude / Anthropic
 Gemini / Google AI
 Llama / Open Source
 LangChain / LlamaIndex
 Pinecone / Pgvector
 AWS / Azure AI


 Fintech Solution
 Core Fintech
 Fintech App Development
 Neobank App Development
 eWallet App Development
 Payment Integration
 Lending Software
 BNPL Solution
 BNPL App Development
 Insurance App
 Investment App Dev
 Wealth Management App
 Crypto & DeFi
 DeFi App Development
 Crypto Wallet Dev
 Crypto Exchange Dev
 Trading Platform Dev
 Payments
 Compliance
 RegTech App Dev
 Fraud Detection
 Lending Ecosystem
 P2P Lending Platform
 Mortgage Lending
 Engagement
 Outsourcing Dev


 Mobile Development
 Mobile App Dev
 iOS App Development
 Android App Development
 React Native
 Flutter Development
 Web Development
 Node.js Development
 React.js Development
 Angular Development
 PHP / Laravel
 App Services
 UI/UX Design
 App Maintenance
 By Stage
 MVP Development
 Industry Solutions
 Healthcare App Dev
 Education App Dev
 Travel App Dev
 Real Estate App Dev
 Logistics Software
 Social Media App


 Hire Mobile Developers
 Hire iPhone Developers
 Hire Android Developers
 Hire React Native Devs
 Hire Flutter Developers
 Hire Web Developers
 Hire Node.js Developers
 Hire Angular Developers
 Hire PHP Developers
 Hire Laravel Developers
 How It Works
 Pre-Vetted Developers
 Ready In 48 Hours
 NDA From Day One
 Replace Guarantee

 Company
 About Us
 Portfolio
 Case Studies
 Blog / Insights
 Careers
 Contact Us
 Recognition


 Offices


TL;DR
- The best PayPal alternatives depend on your use case: Wise for international transfers, Venmo or Zelle for personal P2P, Square for in-person retail, Payoneer for freelancers, and Stripe or Adyen for enterprise/developers.
- PayPal’s US merchant fees vary by payment method, with standard credit and debit card payments at 2.99% + $0.49 and PayPal Checkout and Pay with Venmo at 3.49% + $0.49. International commercial transactions add a 1.50% surcharge.
- Venmo now has 100+ million active accounts and, as recorded in March 2026, it supports international transfers to 90 countries via PayPal’s network.
- Limits, fees, and features on all of these platforms often change – treat each number here as a starting point, and confirm current rates before committing.
- Nimble AppGenie builds custom payment and eWallet platforms when an off-the-shelf alternative doesn’t fit your business model.
Years ago, we were required to carry cash to make payments or buy something. eWallet apps like PayPal changed that, making transactions secure and convenient with one tap.
But PayPal is not the right fit for everyone – holds, fees, and support experiences vary, so people look for alternatives. For businesses, that gap is also an opportunity: the first step is to understand what these tools do well before you build an app like PayPal.
Why Do People Look for PayPal Alternatives?
Users may look for PayPal alternatives because of account holds or freezes, transaction-specific fees, dispute experiences, customer-support concerns, and currency-conversion costs. PayPal states that certain risk-based holds can last up to 30 days, while its India complaint process says payment-related complaints may take up to 15 working days to resolve.
How Did Nimble AppGenie Evaluate These 8 PayPal Alternatives?
Nimble AppGenie compared these PayPal alternatives based on fees, security, payment speed, country availability, and buyer protection. We reviewed their pricing, policies, and features as of September 2026.
What Are PayPal’s Fees in 2026?
PayPal charges:
- 2.99% + $0.49 for standard US credit and debit card payments.
- 3.49% + $0.49 for PayPal Checkout and Pay with Venmo.
- 1.50% additional fee for international commercial transactions.
- Other rates apply to specific payment methods, such as QR Code transactions and PayPal Pay Later.
What Are the Best Alternatives to PayPal in 2026?
Whether you are looking for international transactions or personal payments, here is a comparison of alternatives.
| Tool | Best For | Standard Fee | Security |
| Payoneer | Freelancers, international contractors | Receiving: free via Payoneer balance/local-currency receiving accounts; card-funded payments: up to 3.99% + $0.49; bank withdrawals: $1.50 for eligible same-country/local-currency withdrawals or 1.2%–4% for other corridors; card purchases: up to 1.8% without FX / up to 3.5% with FX; annual card fee: $29.95; annual account fee: $29.95 if less than $6,000 is received in 12 months | 2FA, RSA Adaptive Authentication |
| Stripe | Developers, SaaS, custom checkout | 2.9% + $0.30/transaction | PCI DSS, Radar Fraud Prevention |
| Venmo | Personal P2P payments | Free (bank/balance); 3% for credit card | Purchase protection, bank-backed dispute resolution |
| Square | In-person retail, small business POS | 2.6% + 15¢ in-person; 1% ACH | Encrypted data, PCI compliant |
| Adyen | Enterprise, omnichannel commerce | Interchange + variable markup | ML-based fraud scoring, third-party audits |
| Payline | Small business, all-in-one processing | Interchange + 0.35% + $0.10 for monthly volume under $50K; margin falls to Interchange + 0.15% + $0.08 at $1M+ | Biometric authentication, fraud compensation |
| Wise | International transfers, multi-currency | Variable, no hidden fees; 0.5% cashback on debit card | Money transmitter license, dedicated fraud team |
| Zelle | Free US bank-to-bank transfers | Free (bank-dependent) | Bank-level security, no buyer/seller protection |
Note: Fees checked on September 30, 2026. Fees can vary by country, payment method, transaction volume, currency, and account type. Check each provider’s current pricing before a decision.
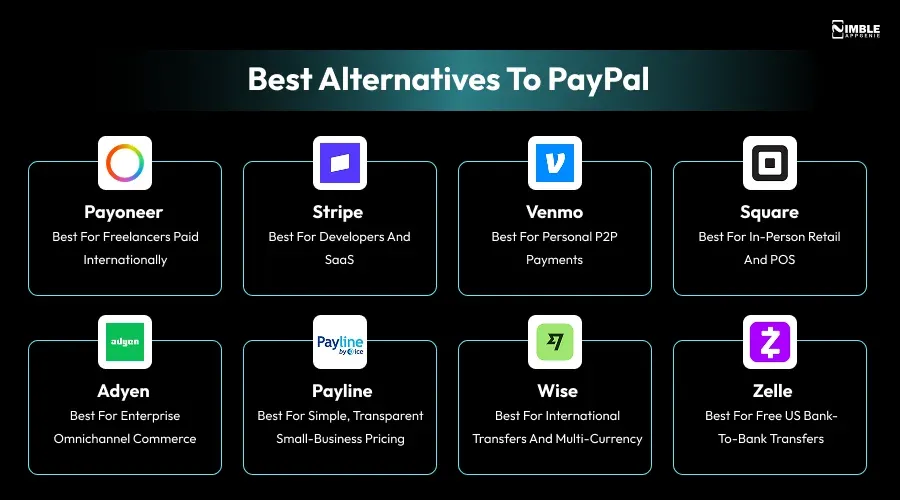
1. Payoneer: Best for Freelancers Paid Internationally
Payoneer is built for businesses and freelancers handling international contractor payments, with a debit card for withdrawals and direct spending, and local receiving accounts in multiple countries. Transactions between Payoneer accounts are free.
2. Stripe: Best for Developers and SaaS
Stripe started as startup-funding infrastructure and grew into one of the most widely adopted payment processors for online payments; a major factor behind this is its genuinely developer-first API. Understanding the difference between a payment processor and a payment gateway clarifies where Stripe fits.
3. Venmo: Best for Personal P2P Payments
Venmo, supported by PayPal, is the default P2P app for a reason: send money with only a QR scan or phone number, add emojis or notes, and see a transaction feed. It has expanded well past its starting days – 100+ million active accounts and, as of March 2026, international transfers to 90 countries through PayPal’s own network. It still lacks business-focused features like reporting and automation.
4. Square: Best for In-Person Retail and POS
Square is designed for businesses that need to accept payments in person as much as online – its card reader plugs into a phone to become a mobile register, and it works offline too. No setup charges or monthly fees make it approachable for small operations.
5. Adyen: Best for Enterprise Omnichannel Commerce
Adyen serves enterprise merchants including Uber, eBay, and Meta, combining POS, e-commerce, and mobile payments on one platform. In H1 2026, Adyen processed €803.8 billion in volume, up 24% annually, showcasing continued growth among high-volume, large merchants rather than a small-business fit. (Source: Adyen H1 2026 financial results)
6. Payline: Best for Simple, Transparent Small-Business Pricing
Payline offers transparent, all-in-one pricing with fraud prevention and a centralized dashboard for inventory, tracking payments, and customer data – a robust option for businesses that want predictable expenses over aggressive feature sets.
7. Wise: Best for International Transfers and Multi-Currency
Wise focuses on international payments with strong exchange rates, operating more like a money service business than a bank. Multi-currency handling is the key differentiator – our guide on developing a multi-currency wallet covers exactly how to build one. Wise’s debit card earns 0.5% cashback on eligible purchases, and customer funds are held as liquid assets, rather than lent out.
8. Zelle: Best for Free US Bank-to-Bank Transfers
Zelle moves money directly between US bank accounts, generally within minutes, with no fee on either side because it’s bank-to-bank, not balance-based. The tradeoff: transfers are usually irreversible, and there’s no buyer/seller protection, so it is built for people you trust, not commercial transactions.
- Sending limits: Limits are set by the user’s bank or credit union, so they vary by institution.
- Scam risk: Zelle warns that authorized payments generally cannot be canceled once the recipient is enrolled and recommends using Zelle only with people you know and trust. It does not offer purchase protection.
- Not ideal if: You’re paying an unfamiliar seller, need buyer protection, or need international transfers.
Beyond these 8, Apple Pay, Google Pay, and Amazon Pay are solid general options – see our best digital wallets guide or our Google Pay vs Apple Pay vs Samsung Pay head-to-head comparison.
Which One Should You Pick?
Below are the scenarios which will help you choose the suitable option:
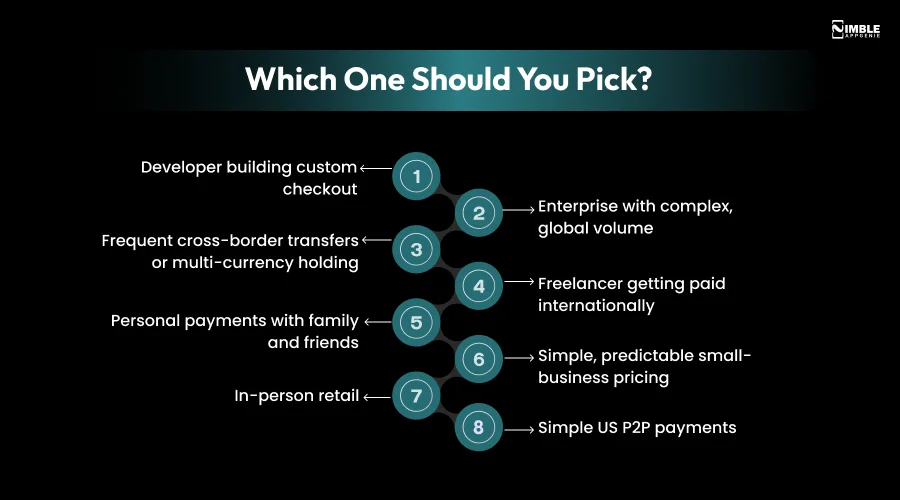
- Developer building custom checkout: Stripe – flexible APIs and developer-focused checkout tools.
- Enterprise with complex, global volume: Adyen – supports global and omnichannel payment setups.
- Frequent cross-border transfers or multi-currency holding: Wise – designed for multi-currency accounts and international transfers.
- Freelancer getting paid internationally: Payoneer or Wise – supports international payments and multi-currency receiving.
- Personal payments with family and friends: Venmo or Zelle – designed for peer-to-peer payments.
- Simple, predictable small-business pricing: Payline – uses transparent interchange-plus pricing.
- In-person retail: Square – combines card processing with POS and in-person business tools.
- Simple US P2P payments: Cash App – supports quick person-to-person payments and optional instant transfers.
When Should You Build a Custom Payment Platform Instead?
When off-the-shelf tools don’t cover your currency combination, compliance requirements, or product model, you should build a custom payment platform. For example, when you want a market-specific DFS platform, build a closed-loop wallet or a white-label payment platform.
Nimble AppGenie has delivered custom payment platforms ranging from $40,000 to $150,000+ for a single-currency MVP and a full multi-currency enterprise wallet, respectively.
If none of these fit or you need a specific feature combination, full control over the experience, and a niche market, building your payment app becomes the most realistic path. Nimble AppGenie’s guide on the cost to build an app like PayPal breaks down what it actually involves.
Conclusion
All eight tools Nimble AppGenie mentioned fill a specific gap:
- Wise for international transfers,
- Square for in-person retail,
- Stripe for developers,
- Adyen for enterprise volume, and
- Payoneer for freelancers
If your use case doesn’t relate to any of these – DFS platform, closed-loop wallet, white-label payment product, or a specific regulatory market – Nimble AppGenie builds custom payments and eWallet platforms designed around your exact requirements.
Nimble AppGenie has delivered 30+ fintech applications across the UAE, UK, East Africa, and India, including cross-border payment platforms, digital wallets, and real-money gaming payment stacks.
FAQs
Some of the best alternatives to PayPal are Stripe, Payoneer, Venmo, Square, Wise, Payline, Adyen, and Zelle. The right one depends on whether you need international payments, personal P2P, or business processing.
PayPal may not be the right fit for every business or individual. Transaction fees can vary by payment type and location, while account holds or payment limitations can temporarily restrict access to funds. Users may also look for alternatives when they need lower cross-border fees, faster payouts, specific payment methods, or features better suited to their business model. By comparing alternatives, Nimble AppGenie has helped users choose a payment platform that matches their transaction volume, payment needs, and geographic requirements.
PayPal’s biggest competitors include Stripe (for online businesses and developers), Wise (for international transfers), and Cash App and Zelle (for personal P2P payments in the US).
Both have their advantages. PayPal is a familiar, widely recognized platform for everyday payments, while Stripe is built for developers and businesses processing high transaction volumes through custom checkout flows.
For free, fast transfers between US bank accounts you trust, Zelle has no fees and no PayPal-style holds. It offers no buyer/seller protection, though, so it’s not suited for commercial transactions the way PayPal is.
Niketan Sharma, CTO, Nimble AppGenie, is a tech enthusiast with more than a decade of experience in delivering high-value solutions that allow a brand to penetrate the market easily. With a strong hold on mobile app development, he is actively working to help businesses identify the potential of digital transformation by sharing insightful statistics, guides & blogs.