Free Consultation
 PCI-DSS Compliant
 GDPR Ready
 ISO 27001
 NDA Protected
 AI Services
 AI App Development
 Generative AI Development
 AI Chatbot Development
 AI Integration Services
 AI For Fintech
 AI Financial Assistant Solution
 AI Insurance Agent Development
 Tech Stack
 OpenAI / GPT-4
 Claude / Anthropic
 Gemini / Google AI
 Llama / Open Source
 LangChain / LlamaIndex
 Pinecone / Pgvector
 AWS / Azure AI


 Fintech Solution
 Core Fintech
 Fintech App Development
 Neobank App Development
 eWallet App Development
 Payment Integration
 Lending Software
 BNPL Solution
 BNPL App Development
 Insurance App
 Investment App Dev
 Wealth Management App
 Crypto & DeFi
 DeFi App Development
 Crypto Wallet Dev
 Crypto Exchange Dev
 Trading Platform Dev
 Payments
 Compliance
 RegTech App Dev
 Fraud Detection
 Lending Ecosystem
 P2P Lending Platform
 Mortgage Lending
 Engagement
 Outsourcing Dev


 Mobile Development
 Mobile App Dev
 iOS App Development
 Android App Development
 React Native
 Flutter Development
 Web Development
 Node.js Development
 React.js Development
 Angular Development
 PHP / Laravel
 App Services
 UI/UX Design
 App Maintenance
 By Stage
 MVP Development
 Industry Solutions
 Healthcare App Dev
 Education App Dev
 Travel App Dev
 Real Estate App Dev
 Logistics Software
 Social Media App


 Hire Mobile Developers
 Hire iPhone Developers
 Hire Android Developers
 Hire React Native Devs
 Hire Flutter Developers
 Hire Web Developers
 Hire Node.js Developers
 Hire Angular Developers
 Hire PHP Developers
 Hire Laravel Developers
 How It Works
 Pre-Vetted Developers
 Ready In 48 Hours
 NDA From Day One
 Replace Guarantee

 Company
 About Us
 Portfolio
 Case Studies
 Blog / Insights
 Careers
 Contact Us
 Recognition


 Offices


TL;DR
- Starting an eWallet business means choosing between your own payment license or a Banking-as-a-Service (BaaS) partner, building a secure and compliant wallet app around a clear target user, and structuring a monetization model all before development begins.
- Before writing a single feature list, decide whether to get your own money-transfer/EMI license or launch on a BaaS partner’s rails; this choice affects your timeline and budget more than almost any other decision.
- Security isn’t optional: tokenization, biometric verification, and fraud monitoring need to be part of the architecture from day one, not bolted on post-launch.
- Realistic budgets run from roughly $25,000 for a lean MVP to $250,000+ for a fully-featured, multi-market wallet, and timelines stretch further once licensing is factored in.
- Nimble AppGenie has taken 150+ fintech ideas from concept to launch, including the licensing and BaaS-partner decisions covered in this guide.
A founder looking to start an eWallet business chooses between its own payment license and a Banking-as-a-Service (BaaS) partner to build a compliant, secure wallet app for a clear target user and to structure a monetization model – all before building a single feature.
Fintech founders eyeing this space still ask the same two questions: how much will this cost, and how fast can I get to market? The honest answer to both depends less on your feature list than on that first decision, licensing versus BaaS, which most “how to start” guides skip completely. Get that call wrong, and witness a six-month launch quietly turn into eighteen.
This guide includes a roadmap that walks you through that decision, realistic timelines and costs, the complete build process, and how businesses like Venmo, PayPal, and Cash App got it right. This way, you can plan well with the full plan, not just the app-development part.
Just How Big Is the eWallet Opportunity?
Below, we have created a clear picture of the numbers rather than a pile of stats from distinct years:
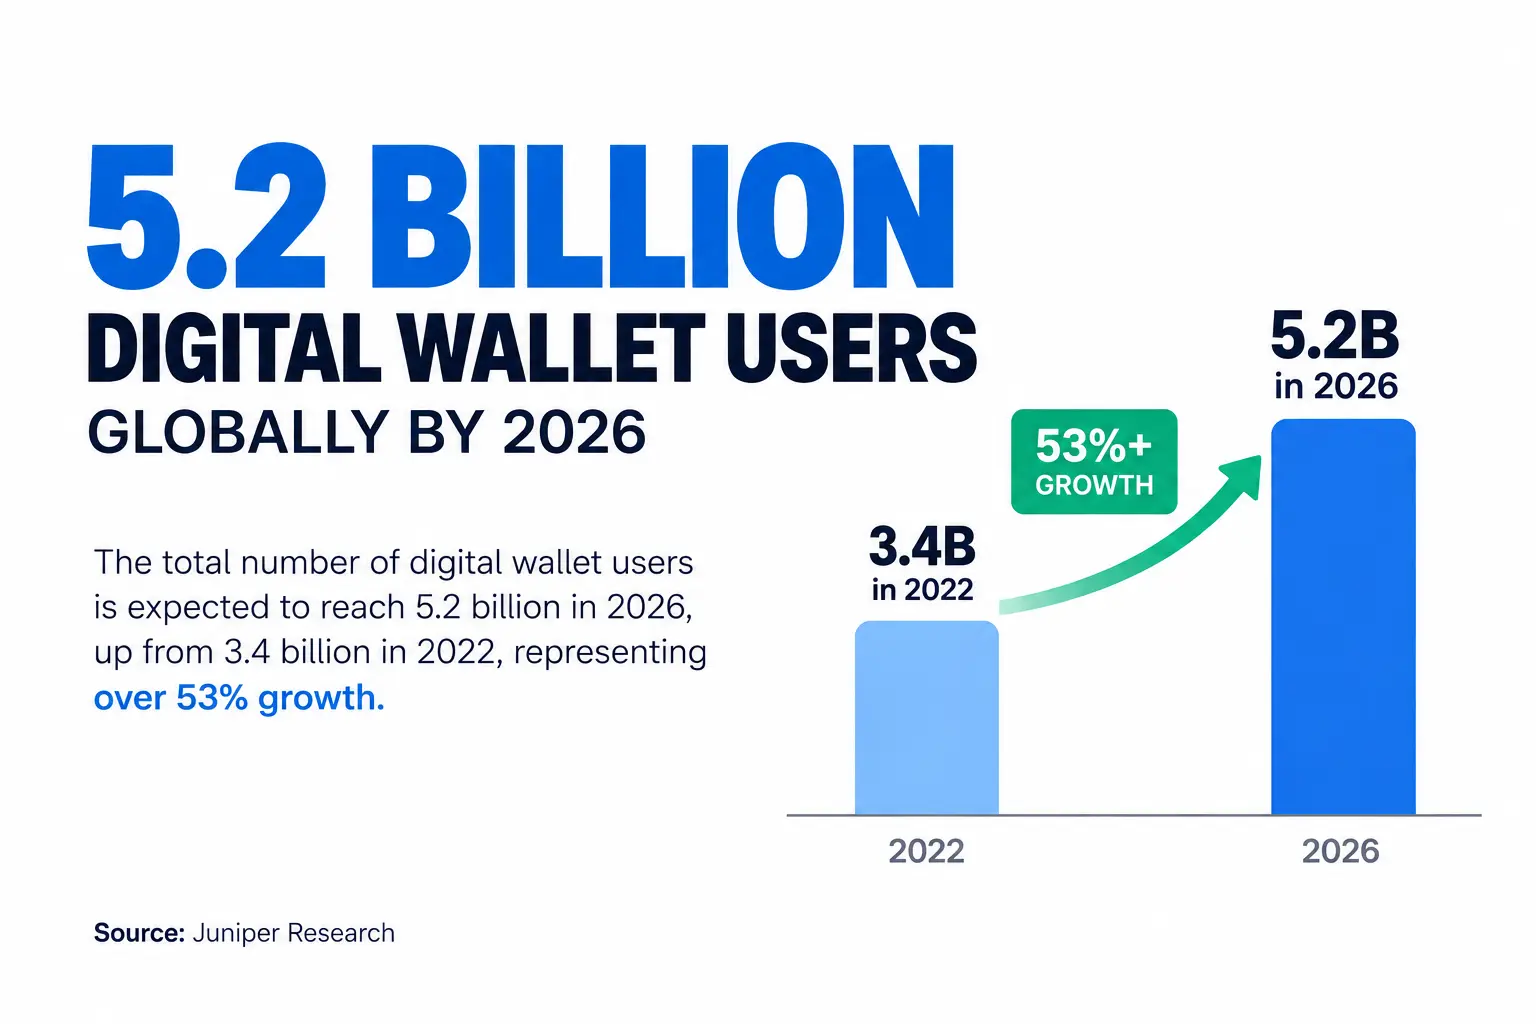
- The number of digital wallet users globally increased from 3.4 billion in 2022 to an expected 5.2 billion by 2026, per Juniper Research.
- The total value of digital wallet transactions is predicted to grow from $7.5 trillion in 2022 to over $12 trillion by 2026 – about a 60% surge in four years, according to Juniper Research.
- Considering the broader mobile/digital wallet market, one widely cited projection reached $1.04 trillion in 2019 and will reach $7.58 trillion by 2027 – an approximately 28% growth rate year-over-year – per Allied Market Research.
Full breakdowns, including regional splits, are in our eWallet app statistics report.
What Is an eWallet App?
An eWallet, digital wallet, or mobile wallet replicates a physical wallet digitally – running transactions, storing funds, and tracking spending from a browser or phone instead of a leather billfold.
The commercial opportunity isn’t in building “another payment app” – it’s in identifying a gap an existing wallet leaves open, whether that’s a missing feature set, a niche user base, or a market still underserved by the big players.
Why the Timing Favors Starting Now
- Consumer habits have shifted: tap-to-pay and in-app checkout are now the default expectation at the point of sale, not a fallback option, which pressures businesses to route customers through slower payment flows.
- Regulators are actively encouraging this shift, not only tolerating it – frameworks like the EU’s PSD2 are specifically designed to open up and secure digital payments infrastructure, removing the barrier for new entrants.
- Wallets change the security equation, not only the convenience one – biometric authentication and tokenization remove the raw card number from the transaction completely, which is a meaningfully distinct risk profile from a swiped or typed-in card.
- The user growth curve is not slowing – a market still adding around 1.8 billion new wallet users between 2022 and 2026 is still much in its acquisition phase, not its consolidation phase.
Should You Get Your Own License, or Partner With a BaaS Provider?
This decision affects your budget, launch date, and level of operational control.
Option A: Get Licensed Yourself
This generally means an E-Money Institution (EMI) license in the UK/EU or a state-by-state Money Transmitter License (MTL) in the US. It offers you complete control over the product and economics, but it is slow and capital-intensive. So, expect anywhere from 6 to 18 months of regulatory work before you can transfer your money, plus ongoing compliance expenses.
Option B: Partner With a Banking-as-a-Service (BaaS) Provider
A licensed BaaS partner helps launch within its regulatory limitations, handling core banking and compliance infrastructure while you create the customer-facing product. This trades some margins and long-term control for a drastically shorter runway – many wallets built this way reach market in months rather than a year.
| Factor | Your Own License | BaaS Partnership |
| Time to Launch | 6–18+ months | 2–6 months |
| Upfront Cost | High (legal, capital reserves, compliance staff) | Lower; often revenue-share or per-transaction fees |
| Operational Control | Full control over product and terms | Shared — bound by partner’s rules and risk appetite |
| Best For | Well-funded ventures planning long-term scale | Startups validating demand before heavy capital commitment |
A Quick Note on Regional Licensing
In the US, money transmission is regulated state by state, so a nationwide launch means securing (or partnering under) various individual MTLs.
In the UK and EU, an EMI license issued by a single regulator (the FCA in the UK) can passport across the bloc, which is one reason many European fintechs pursue their license sooner than US counterparts do.
Either path also touches broader fintech regulatory requirements around KYC and AML that apply regardless of which route you choose.
Groundwork Before Development Begins
With the licensing question settled, a few foundation steps should still take place before writing any code.
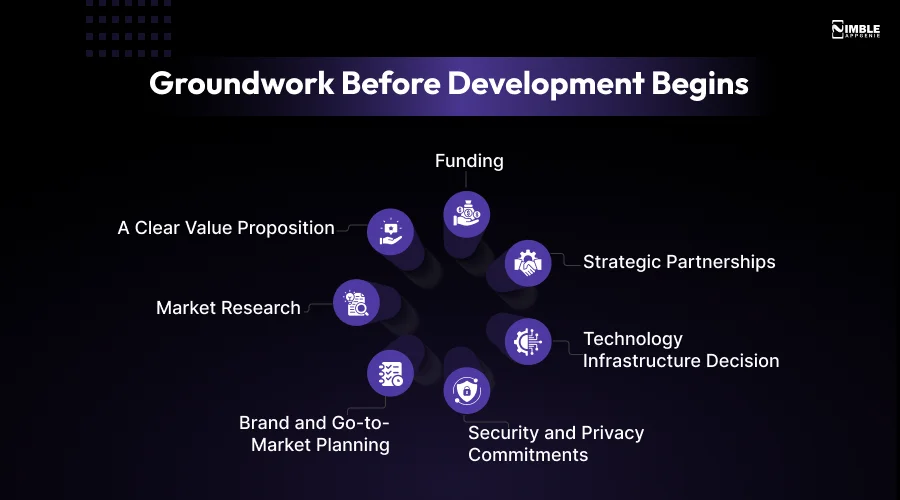
1. Market Research
Go deeper into mobile app market research to understand demographics, competitors, and unmet needs.
2. A Clear Value Proposition
What makes your wallet worth switching to, not only trying once.
3. Funding
Map your capital requirements and explore app funding options, from bootstrapping to venture capital.
4. Strategic Partnerships
Banks, merchants, and payment processors that extend your credibility and reach.
5. Technology Infrastructure Decision
Blockchain, cloud, or traditional databases, picked for scalability as much as for launch-day needs.
6. Security and Privacy Commitments
Encryption and two-factor authentication as baseline needs, not premium add-ons.
7. Brand and Go-to-Market Planning
A wallet is a trust product before it is a utility; branding needs to reflect that.
Building the App: A 10-Step Development Process
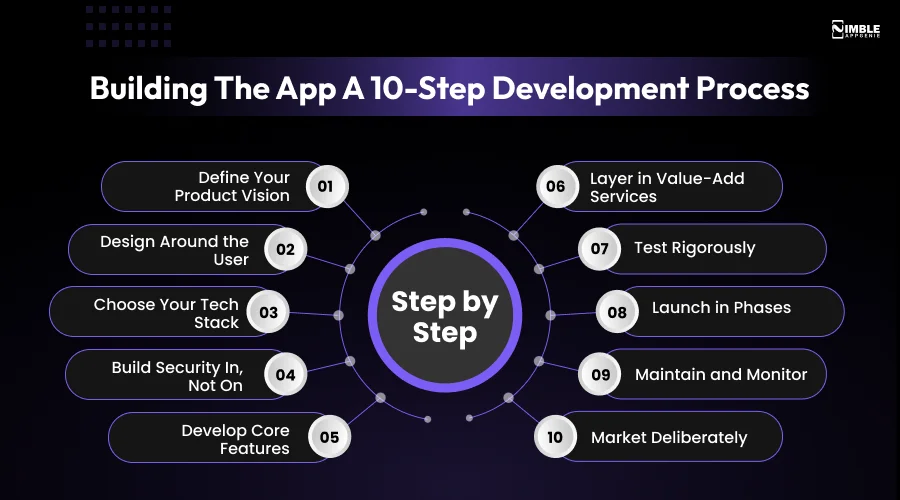
- Define Your Product Vision: Settle on your unique eWallet idea and how it differs from what is already out there.
- Design Around the User: Invest in UX/UI research and testing before locking in flows.
- Choose Your Tech Stack: Front end, back end, databases, and security protocols; see our fintech tech stack guide for the options.
- Build Security In, Not On: Encryption, robust authentication, and fraud detection, aligned with PCI-DSS requirements from the start.
- Develop Core Features: Registration, balance checks, bank-linking, transaction history, and P2P transfers. Our eWallet features guide covers the full list.
- Layer in Value-Add Services: Mobile recharges, bill pay, financial insights, and loyalty programs that deepen engagement.
- Test Rigorously: Performance, functional, and user-acceptance testing, well before a public launch.
- Launch in Phases: A beta rollout surfaces issues while the stakes are still low.
- Maintain and Monitor: Ongoing performance monitoring and updates keep the wallet relevant and secure.
- Market Deliberately: A structured acquisition plan across digital channels, PR, and influencers.
Realistic Timeline
Stack these stages together, and a specific path looks like: 1-2 months of research and planning, 2-6 months for a BaaS-backed MVP (or 6-18+ months if pursuing your own license in parallel), 3-6 months of development and testing, and an ongoing cycle of iteration post-launch. A BaaS-backed MVP can actually reach the market in 6 months; a self-licensed build rarely does.
Common Roadblocks and How to Handle Them
| Challenge | Practical Fix |
| User onboarding drop-off | Shorten sign-up, allow phone/email login, show the value proposition on screen one |
| Bank/gateway integrations | Prioritize the most-used banks first; test pre-launch thoroughly; offer fallback payment options |
| Keeping pace with tech | Ship small, frequent updates rather than infrequent large releases |
| Regulatory friction (KYC) | Explain why documents are needed; automate verification where possible |
| Security threats | Encryption, 2FA, biometric access, and real-time transaction alerts as standard |
| Market competition | Differentiate with cashback, budgeting tools, or faster refunds rather than competing on price alone |
| Building user trust | Display security badges, partner banks, and transparent fee structures upfront |
| Scaling smoothly | Cloud-native infrastructure and proactive performance monitoring |
Many of these are common mobile app development challenges, but a dedicated development team experienced in fintech apps can identify and address them earlier.
What the Category Leaders Got Right
- Alipay: Became a super-app by folding payments, insurance, and investing into one experience.
- PayPal: Expanded from a simple processor into a full financial platform without losing ease of use.
- Venmo: Turned P2P payments social, building a habit loop most wallets never attempt. (See what it would take to build something similar)
- Apple Pay: Made NFC payments mainstream by prioritizing privacy and device-level security. (Full cost breakdown: building an app like Apple Pay.)
- Google Pay: Leaned on ecosystem integration rather than competing on features alone.
- WeChat Pay: Proved a wallet can thrive embedded inside a social platform rather than standing alone.
- Cash App: Stretched “payment app” into direct deposits, crypto, and investing. (See our Cash App development guide.)
What Does It Actually Cost?
An eWallet app generally costs $25,000 to $100,000 to build, though total business launch costs increase once every category below is accounted for:
| Expense Category | Cost Range | Details |
| Market Research & Planning | $5,000 – $20,000 | Consultants and research to validate the opportunity |
| Technology & Infrastructure | $50,000 – $150,000+ | Front-end, back-end, database, security, and payment gateway integration |
| Legal & Compliance | $10,000 – $50,000 | KYC/AML compliance, PCI-DSS alignment, IP protection |
| Licensing & Partnerships | Varies widely | Depends heavily on the license-vs-BaaS decision above |
| Marketing & Branding | $10,000 – $50,000 | Brand identity, website, and launch campaigns |
| Ongoing Operations | Varies | Staff, tooling, office costs, and day-to-day overhead |
How to Actually Make Money From It
Check out ten major, proven eWallet monetization strategies worth building into your revenue:
| Model | How It Works |
| Transaction fees | A flat or percentage-based fee per transaction processed |
| Merchant services | Fees for transaction tools, insights, and loyalty features sold to merchant partners |
| Premium features | Free core wallet, paid upgrades like higher limits or advanced tools |
| Subscriptions | Recurring fee for zero transaction costs or priority support |
| Interest on stored funds | Where regulation allows, interest earned on aggregated balances |
| Cross-selling financial products | Loans, insurance, or investments offered through partner institutions |
| In-app advertising | Relevant, non-intrusive ads placed within the wallet experience |
| Data analytics | Anonymized, consent-based transaction insights sold for market research |
| White-labeling | Licensing your wallet platform to other businesses |
| FX services | Margin on currency conversion for cross-border transactions |
Where Nimble AppGenie Fits Into This Roadmap
Nimble AppGenie has converted more than 150 fintech ideas from concept to real solutions, including the licensing-versus-BaaS decision this guide opened with.
We build every wallet under PCI-DSS, ISO 27001, and GDPR requirements as standard practice, not as a late-stage patch. Besides, our teams have hands-on experience integrating BaaS-backed launches and self-licensed architectures.
If you are still struggling to decide between building your tech stack or leaning on ready-made e-wallet development expertise, that’s precisely the kind of scoping conversation worth having before development starts.
Conclusion
Starting an eWallet business in 2026 is more about sequencing the right decisions in the right order: licensing strategy first, security and technical architecture second, growth and monetization third.
Founders who skip the licensing conversation are the ones whose “6-month launch” quietly becomes a year and a half. Get that piece right early, and the rest of the roadmap becomes a lot more executable.
FAQs
In most cases, yes, you need either your own EMI license (UK/EU) or a Money Transmitter License (US), or you operate under a licensed Banking-as-a-Service partner’s regulatory coverage. Very few eWallet businesses can legally move customer funds without one of these two paths.
Rising smartphone adoption, a global shift toward cashless payments, and demand for more secure, convenient payment methods are the core drivers, with the digital payments market on track to exceed $10 trillion by the end of 2026.
A BaaS-backed MVP can often reach the market in around 6 months. Pursuing your own license typically adds 6 to 18 months or more before you can legally handle customer funds directly, on top of development time.
Key steps include market research, deciding between your own license and a BaaS partnership, securing funding, building bank and processor partnerships, and developing the app itself with security built in from the start.
Well-funded ventures planning long-term scale often benefit from owning their license eventually, while startups validating demand typically launch faster and cheaper through a BaaS partnership first.
App development alone typically runs $25,000 to $100,000, while total launch costs, including legal, compliance, licensing, and marketing, commonly reach $100,000 to $250,000 or more, depending on scope.
PayPal, Alipay, Venmo, Google Pay, Apple Pay, WeChat Pay, and Cash App each demonstrate different winning strategies, from super-app integration to social payment features.
Common models include transaction fees, merchant services, premium features, subscriptions, interest on stored funds, cross-selling financial products, advertising, data analytics, white-labeling, and FX services.
Niketan Sharma, CTO, Nimble AppGenie, is a tech enthusiast with more than a decade of experience in delivering high-value solutions that allow a brand to penetrate the market easily. With a strong hold on mobile app development, he is actively working to help businesses identify the potential of digital transformation by sharing insightful statistics, guides & blogs.