

 Free Consultation
 PCI-DSS Compliant
 GDPR Ready
 ISO 27001
 NDA Protected
 AI Services
 AI App Development
 Generative AI Development
 AI Chatbot Development
 AI Integration Services
 AI Consulting Services
 AI For Fintech
 AI Financial Assistant Solution
 AI Insurance Agent Development
 Tech Stack
 OpenAI / GPT-4
 Claude / Anthropic
 Gemini / Google AI
 Llama / Open Source
 LangChain / LlamaIndex
 Pinecone / Pgvector
 AWS / Azure AI


 Fintech Solution
 Core Fintech
 App Development
 Neobank Solutions
 eWallet Solutions
 Lending Software
 Banking Solutions
 BNPL Solutions
 BNPL Solutions
 Insurance App
 Wealth Management
 Crypto & DeFi
 Blockchain Development
 Payroll Software
 DeFi Solutions
 Crypto Wallet
 Crypto On/Off Ramp
 Crypto Exchange
 Trading Platform
 Payments
 Compliance
 Regulations & Compliance
 Fraud Detection
 Lending Ecosystem
 P2P Lending Platform
 Mortgage Software
 Engagement
 Fintech Outsourcing


 Mobile Development
 Mobile App Dev
 iOS App Development
 Android App Development
 React Native
 Flutter Development
 Web Solution
 Node.js Development
 React.js Development
 Angular Development
 App Services
 UI/UX Design
 App Maintenance
 By Stage
 MVP Development
 Industry Solutions
 Healthcare App Dev
 Education App Dev
 Travel App Dev
 Real Estate App Dev
 Logistics Software
 Social Media App


 Hire Mobile Developers
 Hire iPhone Developers
 Hire Android Developers
 Hire React Native Devs
 Hire Flutter Developers
 Hire Web Developers
 Hire Node.js Developers
 Hire Angular Developers
 Hire PHP Developers
 Hire Laravel Developers
 How It Works
 Pre-Vetted Developers
 Ready In 48 Hours
 NDA From Day One
 Replace Guarantee

 Company
 About Us
 Our Work Process
 Portfolio
 Case Studies
 Blog / Insights
 Careers
 Contact Us
 Awards
 Recognition


 Offices


TL;DR
- Mobile payment technology is a set of digital systems, like QR codes, NFC, cloud-based tokenization, and MST, that allow a smartwatch, smartphone, or app to send encrypted payment data instead of a physical card.
- The global mobile payments market was valued at around $2.98 trillion in 2023 and is likely to reach $27.81 trillion by 2032.
- Payments fall into two broad categories: remote payments (P2P transfers, in-app purchases, bill pay) and proximity payments (tap-to-pay, QR at checkout).
- Every transaction depends on encryption and tokenization – the merchant and network never see your actual card number, only a disposable token.
- Nimble AppGenie designs and builds PCI-DSS-compliant e-wallet and mobile payment apps for fintechs, enterprises, and banks – see how it’s done further down this guide.
Whether it’s Google Pay, Apple Pay, Cash App, or PayPal, most people use at least one of these apps weekly, and almost nobody thinks about what happens in seconds between “tap” and “approved.”
Mobile payment technology lives in that gap: a stack of software, hardware, and security protocols, eliminating the need for a wallet full of cards. Now, it processes trillions of dollars annually, becoming a reason for new fintech businesses to keep investing in this space.
This guide breaks down how mobile payments work, the technologies powering them, how they compare, and where the real security risks lie – so you understand the system well enough to not only use it, but build on it.
What Is Mobile Payment Technology?
Mobile payment technology combines hardware and software systems that allow a mobile device, tablet, smartphone, or wearable to initiate and complete a financial transaction without cash or a physical card.
Instead of swiping a card, the device interacts with a payment terminal or remote server using various methods, such as NFC (tap), a mobile wallet app, or a QR code (scan) that connects directly to a payment gateway over the internet.
Behind the scenes, the transaction touches various components: the fintech app or wallet, the cloud-based token vault, the device’s secure element, the acquiring bank’s POS system, the payment network (Visa, Mastercard, etc.), and the issuing bank that approves or declines the payment.
Types of Mobile Payment Technology
Mobile payments make the most of various technologies, each designed to meet different needs. Here’s what powers them:
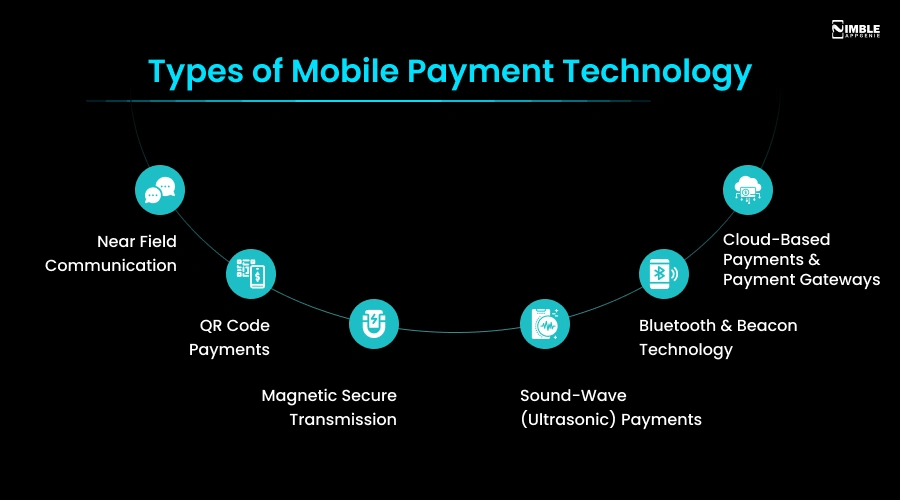
1. Near Field Communication (NFC)
NFC allows two devices to exchange encrypted data when placed within a few centimetres of each other. It’s the technology behind Google Pay, Apple Pay, and most tap-to-pay terminals worldwide – contactless, fast, and the current global standard for in-store payments. Read our guide on NFC mobile payments for the full technical breakdown.
2. QR Code Payments
The merchant or customer scans a QR code to initiate the transaction with no requirement for an NFC chip on either side. This model is dominating in China (WeChat Pay, Alipay), becoming common for P2P transfers and small merchants globally. It needs no special hardware. See our eWallet QR code payment guide for implementation details.
3. Magnetic Secure Transmission (MST)
MST mimics the magnetic strip of a traditional card, allowing a phone “tap” at almost any existing card terminal – even ones without NFC hardware. Samsung Pay uses this as a fallback, offering it wider point-of-sale compatibility than NFC-only wallets.
4. Sound-Wave (Ultrasonic) Payments
This method is most significant in parts of Asia and Africa, but less popular in Western markets. It encodes payment data into an ultrasonic sound signal transmitted between devices, useful where NFC hardware is not standard.
5. Bluetooth & Beacon Technology
Used more for checkout triggers and proximity marketing and less for the payment itself, beacons detect when a customer’s phone is close to a terminal and can pre-populate a payment flow before they even tap.
6. Cloud-Based Payments & Payment Gateways
In-app and remote payments don’t depend on proximity hardware. The app talks directly to a payment gateway, which routes tokenized, encrypted data to the card network and bank over the internet.
Proximity, Remote, P2P, and mPOS: The Four Payment Models
Each mobile payment technology we discussed above benefits one of four transaction models:
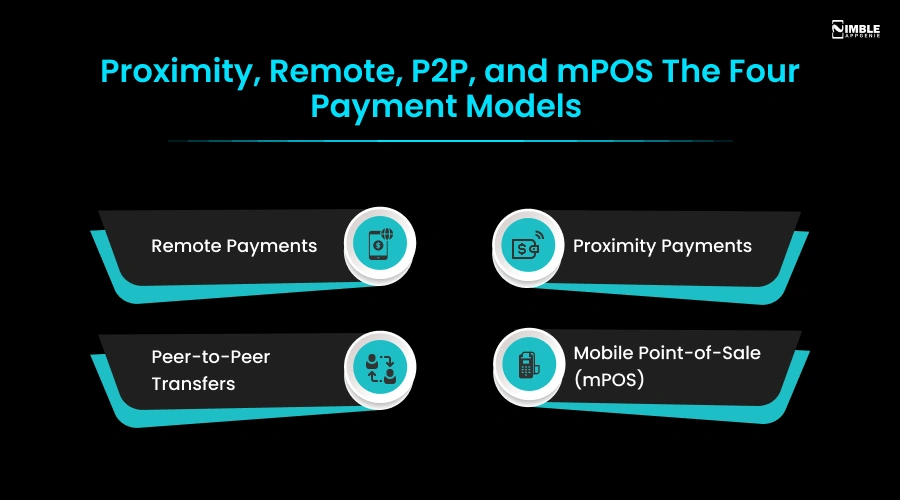
- Remote Payments: In-app purchases, online checkout, and bill pay, where the phone talks to a gateway over the internet, not a nearby terminal.
- Proximity Payments: Tap or scan at a physical checkout (MST, NFC, QR-in-store).
- Peer-to-Peer Transfers: Sending money directly to another person via email, ID, or phone number, as covered in our guide to building a money transfer app.
- Mobile Point-of-Sale (mPOS): The merchant’s side of the equation, where a smartphone or tablet becomes the card terminal, common for small businesses and delivery riders.
How Does a Mobile Payment Transaction Actually Work?
The payment type decides the flow, but here is what happens on a standard proximity (tap-to-pay) transaction:
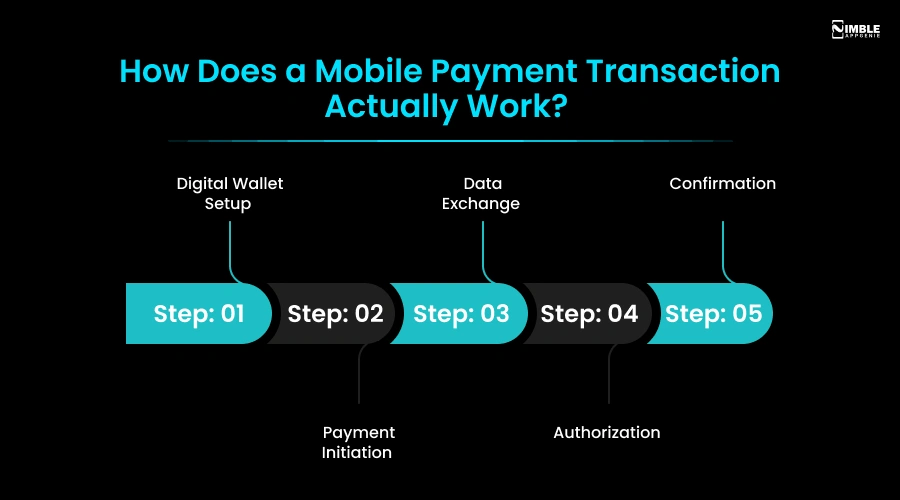
Step 1: Digital Wallet Setup
The user adds a card to a wallet app (Google Pay, Apple Pay, or a custom e-wallet app). The card number is never stored as-is – it’s replaced with a device-specific token.
Step 2: Payment Initiation
The user chooses a card in the wallet and holds their phone near an NFC-enabled terminal, or opens the app to pay remotely.
Step 3: Data Exchange
For NFC/MST: The phone and terminal exchange encrypted data over radio waves in under a second.
For Remote/QR: The app sends the encrypted, tokenized payment request to a payment gateway instead.
Step 4: Authorization
The transaction processing system forwards the tokenized data to the card network and the issuing bank, which checks fraud signals, funds, and account status.
Step 5: Confirmation
The bank approves or declines in real time. The merchant’s POS system receives confirmation, and the customer sees a success screen, generally in 1-3 seconds end to end.
Security & Compliance: What Actually Keeps a Mobile Payment Safe
Security is not an afterthought in mobile payments – it’s the whole reason the model works at scale. Three mechanisms take care of everything:
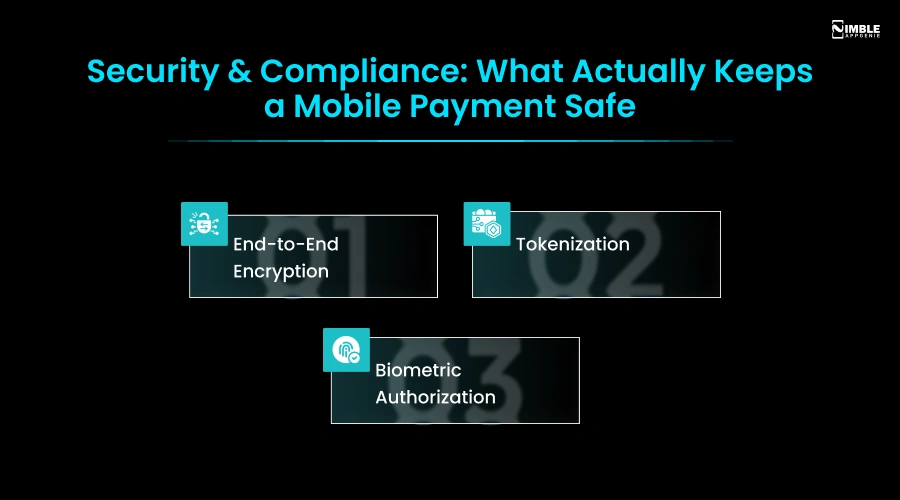
- End-to-End Encryption: Payment data is unreadable to anyone intercepting it between device and bank.
- Tokenization: Your real card number is replaced with a single-use or device-locked token, so a merchant breach never exposes actual card data. See our guide on eWallet payment tokenization.
- Biometric Authorization: Fingerprint, Face ID, or device PIN confirms the person holding the phone is authorized to spend, adding a layer that cash and swiped cards never had.
On the business side, any company integrating or building mobile payments should meet PCI-DSS standards and stay aligned with evolving fintech regulations. Here, fraud detection systems also matter; see how AI-powered fraud detection flags anomalous transactions in real time.
| Note: Nimble AppGenie’s development process is PCI-DSS compliant, ISO 27001 certified, and GDPR-ready by default – the same standards referenced above are built into every payment app we ship. |
| Technology | Best For | Merchant Hardware Needed | Speed | Common Examples |
| NFC | In-store tap payments | NFC-enabled terminal | Under 1 second | Apple Pay, Google Pay |
| MST | Legacy terminal compatibility | Any magnetic-strip reader | 1–2 seconds | Samsung Pay |
| QR Code | Low-hardware markets, P2P, small merchants | None – just a printed/displayed code | 2–4 seconds | Alipay, WeChat Pay |
| Sound-Wave | Regions with low NFC penetration | Speaker + microphone (built-in) | 2–3 seconds | Emerging-market wallets |
Benefits of Mobile Payment Technology
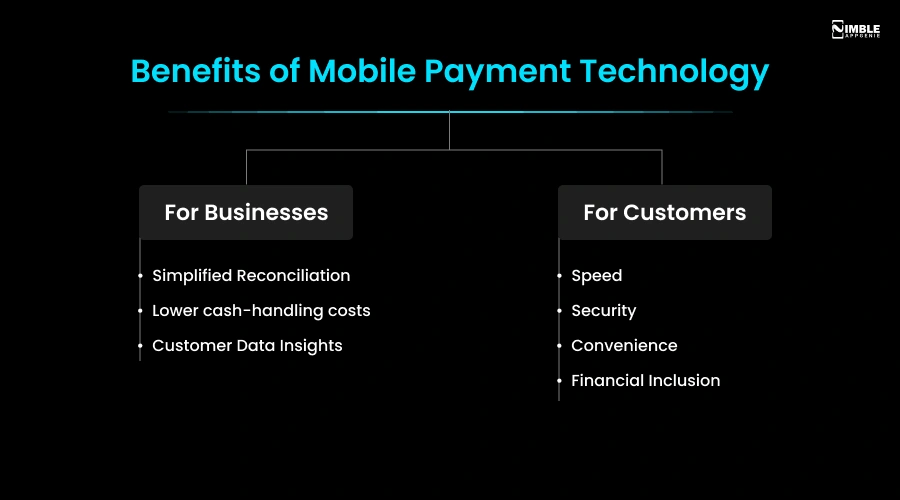
For Businesses
- Simplified Reconciliation: Every transaction is logged automatically.
- Lower cash-handling costs and fewer reconciliation errors.
- Customer Data Insights: Digital transactions generate behavioral data that shapes marketing strategy and retention.
For Customers
- Speed: Tap-and-go checkout can take under a second.
- Security: Tokenization and biometrics reduce fraud exposure vs. a swiped card.
- Convenience: No cash, no cards to carry, no exact change.
- Financial Inclusion: eWallets extend payment access to unbanked users. See the scale of this shift in our eWallet app statistics report.
Challenges of Implementing Mobile Payment Technology
Mobile payments are not friction-free to build or run. The recurring challenges are:
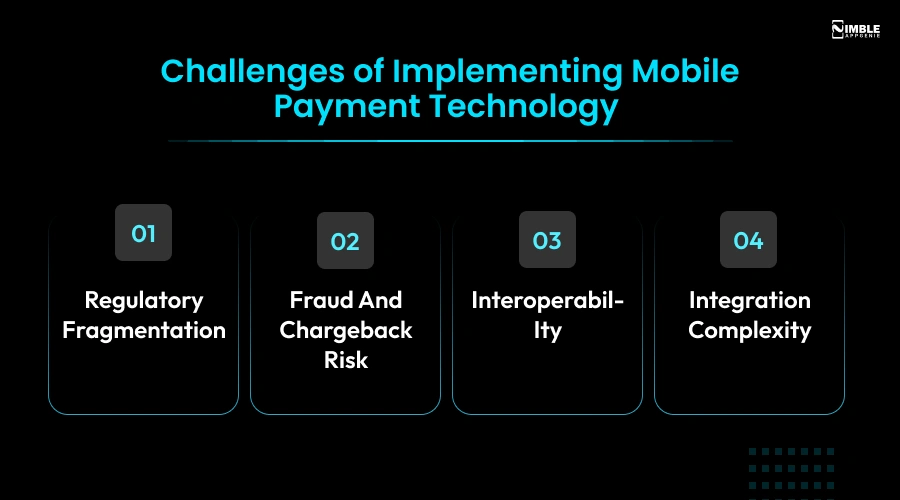
- Regulatory Fragmentation: Compliance requirements differ by country and change frequently.
- Fraud and Chargeback Risk: Needs investment in real-time fraud detection, not just tokenization.
- Interoperability: QR, NFC, and MST ecosystems don’t always interact, complicating multi-region rollout.
- Integration Complexity: Connecting gateways, wallets, and banking rails usually needs a dedicated fintech tech stack and an experienced engineering partner.
How to Implement Mobile Payment Technology: Where Nimble AppGenie Fits In
Most businesses don’t need to build payment rails from the ground up; they only need the right partner to integrate QR, NFC, gateway infrastructure, and tokenization into a product customers actually trust.
At Nimble AppGenie, we have built e-wallet and mobile payment apps for enterprises and fintechs across 50+ countries, with PCI-DSS-compliant architecture, fraud monitoring, and biometric authentication built in from the first sprint, not retrofitted after a security incident. If you are exploring AI-driven fraud and personalization features or need to outsource the complete build, our fintech outsourcing guide covers how that engagement usually works.
Conclusion
Mobile payment technology is not a single feature; it’s a layered system of QR codes, NFC, encryption, tokenization, and banking infrastructure working together in under two seconds per transaction. Understanding every layer is crucial whether you choose to build a wallet or use one.
From your regular tap-to-pay to a complete online payment gateway integration, this infrastructure quietly runs underneath. If you are planning to build on it, understanding how it works is step one, and step two is choosing the right development partner.
FAQs
Mobile payment technology combines hardware and software, NFC, QR codes, MST, tokenization, and payment gateways that let a smartphone or wearable complete a financial transaction without a physical card.
A user initiates payment through a wallet app; the device exchanges tokenized, encrypted data with a terminal or gateway; the transaction is routed to the bank for authorization; and the merchant receives real-time confirmation, typically in one to three seconds.
The main types are proximity payments (NFC tap, MST, in-store QR), remote payments (in-app and online checkout via a payment gateway), peer-to-peer transfers, and mobile point-of-sale (mPOS) for merchants.
Tokenization replaces your actual card number with a disposable or device-specific token during a transaction, so your card data stays hidden from the merchant or is blocked in transit.
Yes, when implemented correctly. Tokenization, end-to-end encryption, and biometric authentication make mobile payments generally more secure than swiped or inserted cards, provided the underlying app meets PCI-DSS compliance standards.
No, NFC is one of several mobile payment technologies, specifically used for proximity/tap payments. QR codes, MST, and sound-wave payments serve the same purpose without needing NFC hardware.
The global mobile payments market was valued at approximately $2.98 trillion in 2023 and is projected to reach $27.81 trillion by 2032, reflecting continued double-digit annual growth through 2026 and beyond.
The main challenges are fraud risk, regulatory fragmentation across markets, interoperability between different payment technologies, and the engineering complexity of securely integrating wallets, gateways, and banking rails.
Niketan Sharma, CTO, Nimble AppGenie, is a tech enthusiast with more than a decade of experience in delivering high-value solutions that allow a brand to penetrate the market easily. With a strong hold on mobile app development, he is actively working to help businesses identify the potential of digital transformation by sharing insightful statistics, guides & blogs.
Table of Contents



No Comments
Comments are closed.