

 Free Consultation
 PCI-DSS Compliant
 GDPR Ready
 ISO 27001
 NDA Protected
 AI Services
 AI App Development
 Generative AI Development
 AI Chatbot Development
 AI Integration Services
 AI Consulting Services
 AI For Fintech
 AI Financial Assistant Solution
 AI Insurance Agent Development
 Tech Stack
 OpenAI / GPT-4
 Claude / Anthropic
 Gemini / Google AI
 Llama / Open Source
 LangChain / LlamaIndex
 Pinecone / Pgvector
 AWS / Azure AI


 Fintech Solution
 Core Fintech
 App Development
 Neobank Solutions
 eWallet Solutions
 Lending Software
 Banking Solutions
 BNPL Solutions
 BNPL Solutions
 Insurance App
 Wealth Management
 Crypto & DeFi
 Blockchain Development
 Payroll Software
 DeFi Solutions
 Crypto Wallet
 Crypto On/Off Ramp
 Crypto Exchange
 Trading Platform
 Payments
 Compliance
 Regulations & Compliance
 Fraud Detection
 Lending Ecosystem
 P2P Lending Platform
 Mortgage Software
 Engagement
 Fintech Outsourcing


 Mobile Development
 Mobile App Dev
 iOS App Development
 Android App Development
 React Native
 Flutter Development
 Web Solution
 Node.js Development
 React.js Development
 Angular Development
 App Services
 UI/UX Design
 App Maintenance
 By Stage
 MVP Development
 Industry Solutions
 Healthcare App Dev
 Education App Dev
 Travel App Dev
 Real Estate App Dev
 Logistics Software
 Social Media App


 Hire Mobile Developers
 Hire iPhone Developers
 Hire Android Developers
 Hire React Native Devs
 Hire Flutter Developers
 Hire Web Developers
 Hire Node.js Developers
 Hire Angular Developers
 Hire PHP Developers
 Hire Laravel Developers
 How It Works
 Pre-Vetted Developers
 Ready In 48 Hours
 NDA From Day One
 Replace Guarantee

 Company
 About Us
 Our Work Process
 Portfolio
 Case Studies
 Blog / Insights
 Careers
 Contact Us
 Awards
 Recognition


 Offices


| Quick Answer: IoT in digital wallets refers to connected devices, smart home systems, cars, smartwatches, and, increasingly, AI agents that use tokenization, sensors, and network connectivity to enable secure payments without a physical card or phone. |
Imagine your smartwatch paying automatically for your car toll, your coffee, and an AI agent restocking your groceries before you even notice you are low. That’s what IoT integration in digital wallets looks like for the first two, and where it is headed for the third.
This guide, written by the fintech experts at Nimble AppGenie, covers how IoT payments actually work, real (and currently active) examples, the 2026 shift toward AI agents making payments on their own, and the security challenges involved.
Understanding the Internet of “Payment”
The Internet of Things (IoT) refers to an interconnected network of devices that communicate together to collect, share, and act on data. These devices range from everyday household items like refrigerators and thermostats to advanced industrial machinery, using sensors, software, and network connectivity to exchange data and perform tasks autonomously.
In the context of IoT payments, this connectivity lets devices facilitate transactions without human intervention – a smart refrigerator automatically reordering groceries when supplies run low, paying through an integrated eWallet app, is the textbook example.
This kind of automation is increasingly tied to offline payments in eWallets, since many connected devices need to transact in environments with spotty or no internet access.
Contactless payments with IoT are already popular for wearables and smart home systems, and that’s before accounting for where the technology is headed next.
Evolution of Digital Wallets
Digital wallets have evolved from simple online payment tools into sophisticated platforms offering a wide range of financial services – in-store payments, peer-to-peer transfers, and loyalty program integration.
IoT integration has pushed this further, letting wallets interact with connected devices like smartwatches and fitness trackers for real-time, on-the-go transactions. Combined with biometric authentication, blockchain, and AI, wallets are becoming more secure, efficient, and personalized, with open-loop payment systems expected to keep growing for the interoperability they offer.
Benefits of a Connected Ecosystem for Digital Wallets
The integration of IoT with eWallets creates a connected ecosystem with real benefits for both consumers and businesses:
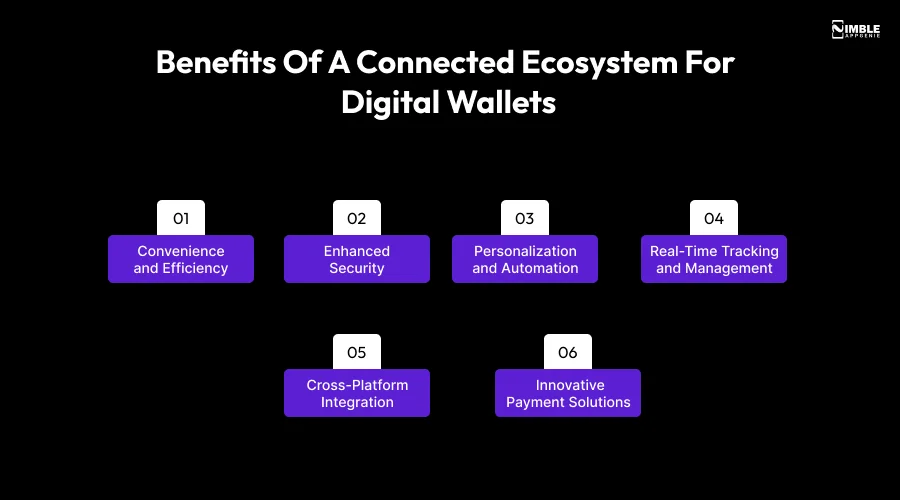
1. Convenience and Efficiency
Devices like smartwatches, fitness trackers, and smart home assistants let users complete transactions with minimal effort.
2. Enhanced Security
Biometric authentication adds a robust layer of security, and IoT devices can employ advanced security protocols to protect sensitive data during transactions.
3. Personalization and Automation
IoT technology enables the collection and analysis of user data, allowing digital wallets to offer personalized experiences, a trend that also makes gamification in digital wallets much easier to implement.
4. Real-Time Tracking and Management
IoT integration allows for real-time tracking of transactions and account balances, with instant notifications helping users manage finances more effectively.
5. Cross-Platform Integration
A connected ecosystem enables interoperability between different platforms and devices, creating a unified payment experience across touchpoints.
6. Innovative Payment Solutions
AI in digital wallets can analyze spending patterns and provide users with insights and recommendations to optimize their financial management.
Real-World Applications: What’s Actually Live in 2026
IoT-powered wallets are no longer a futuristic concept, but not every relevant example cited for this topic is working.
Here is what is typically active right now:
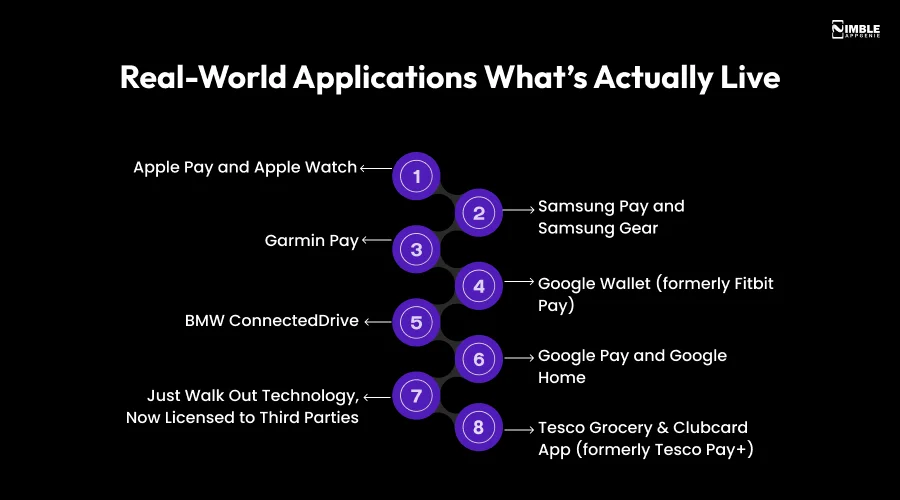
1. Apple Pay and Apple Watch
Apple has smoothly integrated Apple Pay into the Apple Watch, allowing users to make secure payments with just a tap on their wrist.
2. Samsung Pay and Samsung Gear
Samsung Pay, integrated with Samsung Gear smartwatches, works with virtually any terminal that accepts credit cards. The combination of NFC payment technology and MST (Magnetic Secure Transmission) ensures broad compatibility.
3. Garmin Pay
Garmin’s smartwatches support Garmin Pay for on-wrist payments, still actively documented and supported as of 2026 – useful for fitness enthusiasts who choose to leave their wallets at home during workouts.
4. Google Wallet (formerly Fitbit Pay)
Fitbit was completely discontinued on July 29, 2024; all Fitbit devices migrated to Google Wallet.
(Source: Google’s own developer documentation for Fitbit issuers.) Wearable payments on Fitbit hardware now run via the same Google Wallet infrastructure as Android phones.
5. BMW ConnectedDrive
BMW’s ConnectedDrive system integrates digital wallet functionality into its vehicles, allowing drivers to pay for parking, fuel, and tolls directly from their car’s infotainment system.
6. Google Pay and Google Home
Google Pay, integrated with Google Home smart speakers, lets users make voice-activated payments to order products or services, or send money using simple voice commands.
7. Just Walk Out Technology, Now Licensed to Third Parties
In January 2026, Amazon announced that it’s closing its Amazon Go and Amazon Fresh physical stores completely, shifting focus to licensing its “Just Walk Out” cashierless technology to third parties instead – venues, stadiums, and other retailers.
(Source: Amazon’s own January 2026 announcement, reported by TechCrunch) The frictionless-checkout concept itself has not disappeared; it’s no longer Amazon’s retail bet.
8. Tesco Grocery & Clubcard App (formerly Tesco Pay+)
Tesco discontinued the standalone Pay+ app, transforming its scan-and-pay and Clubcard functionality into the unified Tesco Grocery & Clubcard app. The underlying IoT-adjacent capability – scan a barcode, pay, and collect loyalty points in one motion – is still live, only consolidated into fewer apps.
The Next Wave: AI Agents Making Payments
The original idea behind IoT payments – devices making payments for you without any manual action – is becoming standardized, with real-world implementations on their way to launch in 2026.
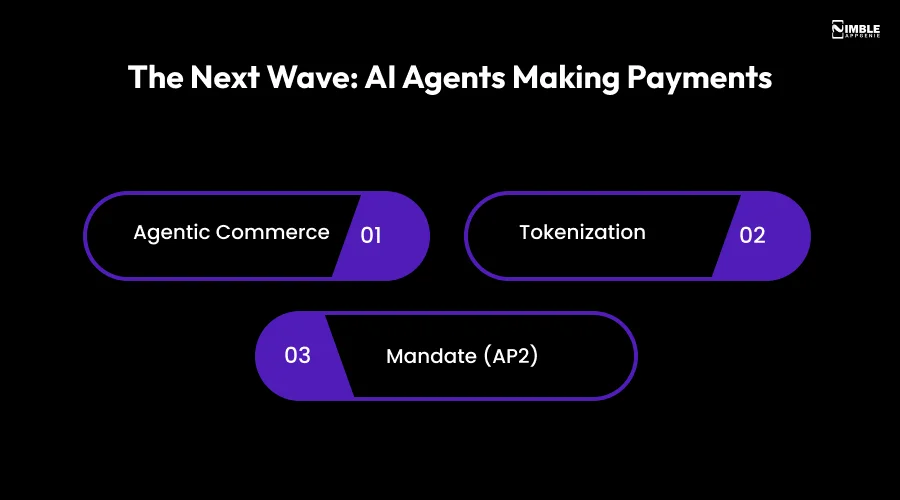
- Agentic Commerce: AI agents autonomously discover, select, and pay for products on a user’s behalf, within limits the user sets in advance.
- Tokenization: Replacing a real card or account number with a disposable, single-use substitute, so the original number stays concealed.
- Mandate (AP2): A cryptographically signed record proving what a user authorized an AI agent to do, and for how much.
| Protocol | Operator | Scope | Status (2026) |
| AP2 (Agent Payments Protocol) | Google (open standard) | Cross-rail agent payments, cards and stablecoins | Live, 60+ partners incl. Mastercard, PayPal, Coinbase, Amex |
| Intelligent Commerce (Trusted Agent Protocol) | Visa | Agent tokenization on Visa’s card rail | Live, 100+ partners, 30+ in sandbox |
| Agent Pay | Mastercard | Agent payments via Mastercard’s Multi-Token Network | Live in the US; global rollout mid-2026 |
| Agentic Commerce Protocol (ACP) | Stripe (with OpenAI) | Single-use, scope-limited tokens for in-chat checkout | Live, moved from preview to production in 2026 |
None of these protocols have reached universal merchant adoption – per industry analysts, the field will remain fragmented through 2026.
But in early 2026, Banco Santander and Mastercard accomplished Europe’s first live, end-to-end payment executed completely by an agent. That single data point is more crucial than the protocol count: this has moved from whitepaper to production.
Where IoT Devices Interact With Wallets Today
IoT devices interact with digital wallets in smart homes, wearables, connected cars, healthcare, retail, and business payment systems. These devices are connected to a wallet to authorize or trigger payments without requiring a physical card or phone.
Smart Home, Wearable, and Automotive Payments
Smartwatches make tap-to-pay possible at transit, vending machines, and coffee shops. Small assistants like Google Home can process voice-activated bill payments. Connected cars can settle tolls and make purchases without driver intervention – all without an underlying device or a phone.
Retail, Health, and Business Applications
Retail environments are approaching frictionless checkout. Health and fitness devices can reorder medical supplies or auto-renew subscriptions.
For businesses, connected POS systems can process payments and update inventory – a genuine extension of thinking through whether to start an eWallet business in this space, where IoT integration and biometrics are quickly becoming the rule rather than the exception.
Integrating IoT Into Digital Wallets: A Technical Overview
How to Integrate IoT Technology
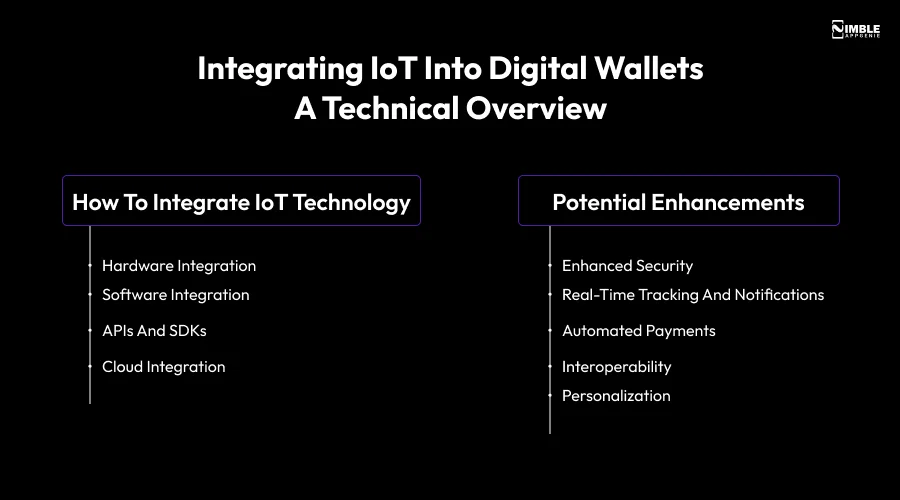
- Hardware Integration: Smartphones, wearables, and smartwatches equipped with NFC chips, compatible with existing POS systems. Securing this device-to-device communication relies primarily on eWallet payment tokenization, keeping sensitive data out of compromised or intercepted devices.
- Software Integration: eWallet applications need APIs that allow communication between the wallet application and IoT devices, with encryption and secure protocols like HTTPS protecting user information.
- APIs and SDKs: E-wallet APIs and SDKs let the digital wallet interact with various IoT devices for real-time transaction tracking and automated payments.
- Cloud Integration: Cloud platforms handle the storage, processing, and analysis of large volumes of IoT-generated data, with secure infrastructure ensuring data integrity and confidentiality.
Potential Enhancements
- Enhanced Security: eWallet security depends on biometric authentication and, increasingly, blockchain for transaction transparency.
- Real-Time Tracking and Notifications: Push notifications and real-time alerts keep users informed.
- Automated Payments: Smart appliances can preorder and pay for supplies when inventory runs low.
- Interoperability: Standards and protocols allow smooth communication between wallets and IoT devices – the same underlying problem the agentic commerce protocols above are now trying to solve at scale.
- Personalization: IoT-generated data enables tailored financial advice and spending alerts.
Securing IoT-Based Payments
Integrating IoT with mobile wallets introduces several technical challenges, particularly concerning security and interoperability.
This section outlines these challenges and provides strategies to address them, ensuring secure and efficient IoT-based payments.
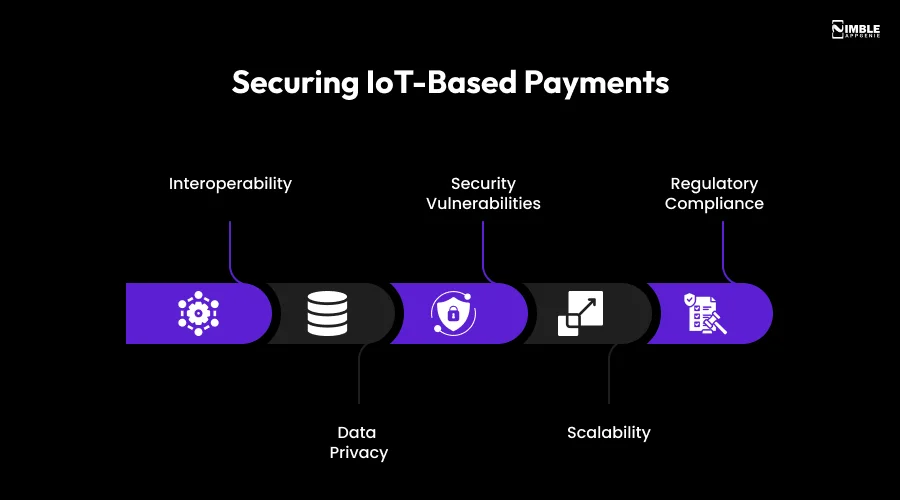
Interoperability
Challenge: Ensuring seamless communication between various IoT devices and digital wallet platforms can be challenging due to different manufacturers and proprietary protocols.
Solution:
- Standardization: Develop and adopt industry-wide standards and protocols to ensure interoperability. Organizations like IEEE and W3C are working on standardizing IoT communication protocols.
- APIs and Middleware: Utilize APIs and middleware solutions to facilitate communication between different devices and platforms, ensuring seamless integration.
Data Privacy
Challenge: IoT devices generate and transmit vast amounts of data, raising significant concerns about data privacy and protection.
Solution:
- Encryption: Implement end-to-end encryption for data transmission between IoT devices and digital wallets to protect sensitive information from unauthorized access.
- Data Minimization: Collect only the necessary data required for transactions and ensure that it is stored securely, adhering to data protection regulations like GDPR and CCPA.
- User Consent: Ensure that users are informed about data collection practices and obtain explicit consent before collecting and using their data.
Security Vulnerabilities
Challenge: IoT devices are often targeted by cyber-attacks due to their limited computational resources and inherent security weaknesses.
Solution:
- Regular Updates: Ensure that IoT devices and digital wallet applications are regularly updated with the latest security patches and firmware updates.
- Multi-Factor Authentication: Implement multi-factor authentication (MFA) to add an extra layer of security, ensuring that only authorized users can access and perform transactions.
- Intrusion Detection Systems: Deploy intrusion detection systems (IDS) to monitor network traffic for suspicious activity and respond promptly to potential threats.
Scalability
Challenge: Managing the scalability of IoT networks and ensuring that digital wallet systems can handle a growing number of connected devices and transactions can be complex.
Solution:
- Cloud-Based Solutions: Leverage cloud computing to provide scalable infrastructure for managing IoT devices and processing transactions. Cloud platforms offer flexibility and resources to handle increased loads efficiently.
- Edge Computing: Utilize edge computing to process data closer to the source, reduce latency and improve the efficiency of IoT networks. This approach can also enhance data privacy and security by minimizing data transmission to central servers.
Regulatory Compliance
Challenge: Navigating the complex landscape of digital wallet regulations and compliance requirements for IoT devices and digital wallet transactions can be daunting.
Solution:
- Compliance Frameworks: Develop and implement compliance frameworks that align with relevant regulations, such as GDPR, CCPA, and PCI DSS. Regular audits and assessments can ensure ongoing compliance.
- Legal Expertise: Engage legal experts who specialize in technology and data privacy laws to ensure that your IoT-enabled digital wallet solutions comply with all applicable regulations and standards.
By addressing these challenges with effective solutions, businesses can ensure the secure and efficient integration of IoT technology into digital wallets, paving the way for innovative and reliable payment solutions.
Nimble AppGenie: Your Partner in IoT-Enabled Digital Wallet Development
Nimble AppGenie specializes in building secure digital wallet solutions that integrate with IoT devices equipped with biometric authentication, NFC, and cloud integration for a powerful, scalable solution.
From concept to deployment, we focus on delivering an efficient, user-friendly payment experience – whether you are building a new digital wallet app or enhancing an existing one.
Conclusion
The integration of IoT technology into digital wallets is transforming how Nimble AppGenie conducts transactions, making them more secure, seamless, and efficient – from wearable payments to smart home systems, and today toward AI agents transacting on our behalf under evolving standards like Agent Pay and AP2.
The examples change more quickly than the underlying trend, which is exactly why it is worth checking which “real-world” examples are still real before building against them.
FAQs
An IoT digital wallet is a digital payment solution integrated with IoT devices, enabling seamless, automated transactions through connected devices without requiring direct human interaction for every payment.
IoT devices enhance digital wallets by providing real-time transaction tracking, automated payments, enhanced security through biometric authentication, and interoperability across platforms and devices.
Security measures include end-to-end encryption, biometric authentication, regular software updates to patch vulnerabilities, and intrusion detection systems to monitor for suspicious activity.
Yes, in limited but real deployments. Mastercard and Santander completed what’s reported as Europe’s first live end-to-end AI agent payment in early 2026, and protocols like Google’s AP2, Visa’s Intelligent Commerce, and Stripe’s ACP are live or in active pilots with major payment networks.
No. Fitbit Pay was discontinued on July 29, 2024, and all supported devices migrated to Google Wallet instead.
Yes, IoT digital wallets can handle automated billing for recurring services such as utility bills and subscriptions, reducing the risk of late payments through scheduled, automatic transactions.
Nimble AppGenie offers digital wallet development services, including IoT integration, ensuring the application is secure, user-friendly, and capable of interacting with various connected devices.
Key challenges include interoperability between different devices and platforms, data privacy, security vulnerabilities, and regulatory compliance, addressed through industry standards, encryption, cloud/edge computing, and compliance frameworks.
Niketan Sharma, CTO, Nimble AppGenie, is a tech enthusiast with more than a decade of experience in delivering high-value solutions that allow a brand to penetrate the market easily. With a strong hold on mobile app development, he is actively working to help businesses identify the potential of digital transformation by sharing insightful statistics, guides & blogs.
Table of Contents



No Comments
Comments are closed.