

 Free Consultation
 PCI-DSS Compliant
 GDPR Ready
 ISO 27001
 NDA Protected
 AI Services
 AI App Development
 Generative AI Development
 AI Chatbot Development
 AI Integration Services
 AI Consulting Services
 AI For Fintech
 AI Financial Assistant Solution
 AI Insurance Agent Development
 Tech Stack
 OpenAI / GPT-4
 Claude / Anthropic
 Gemini / Google AI
 Llama / Open Source
 LangChain / LlamaIndex
 Pinecone / Pgvector
 AWS / Azure AI


 Fintech Solution
 Core Fintech
 App Development
 Neobank Solutions
 eWallet Solutions
 Lending Software
 Banking Solutions
 BNPL Solutions
 BNPL Solutions
 Insurance App
 Wealth Management
 Crypto & DeFi
 Blockchain Development
 Payroll Software
 DeFi Solutions
 Crypto Wallet
 Crypto On/Off Ramp
 Crypto Exchange
 Trading Platform
 Payments
 Compliance
 Regulations & Compliance
 Fraud Detection
 Lending Ecosystem
 P2P Lending Platform
 Mortgage Software
 Engagement
 Fintech Outsourcing


 Mobile Development
 Mobile App Dev
 iOS App Development
 Android App Development
 React Native
 Flutter Development
 Web Solution
 Node.js Development
 React.js Development
 Angular Development
 App Services
 UI/UX Design
 App Maintenance
 By Stage
 MVP Development
 Industry Solutions
 Healthcare App Dev
 Education App Dev
 Travel App Dev
 Real Estate App Dev
 Logistics Software
 Social Media App


 Hire Mobile Developers
 Hire iPhone Developers
 Hire Android Developers
 Hire React Native Devs
 Hire Flutter Developers
 Hire Web Developers
 Hire Node.js Developers
 Hire Angular Developers
 Hire PHP Developers
 Hire Laravel Developers
 How It Works
 Pre-Vetted Developers
 Ready In 48 Hours
 NDA From Day One
 Replace Guarantee

 Company
 About Us
 Our Work Process
 Portfolio
 Case Studies
 Blog / Insights
 Careers
 Contact Us
 Awards
 Recognition


 Offices


| Quick Answer: A payment gateway securely captures and transmits a customer’s payment information; a payment processor handles the back-end work of authorizing, clearing, and settling the transfer of funds – most businesses need both, often from the same provider. |
TL;DR
- A gateway is the main door (capturing and encrypting card data); a processor is the back office (authorizing and settling the money).
- Many modern providers – Square, Stripe, Adyen – now offer both functions packed together; that’s why the line between them has blurred for most businesses.
- The payments industry witnessed a major consolidation move when Global Payments completed its acquisition of Worldpay in January 2026. The combined company now serves 6+ million merchant locations and processes about $3.7 trillion in yearly payment volume across 175+ countries. (Source: Global Payments)
- Stripe processed $1.9 trillion in total payment volume in 2025, up 34% from $1.4 trillion in 2024. (Source: Stripe)
- Nimble AppGenie builds and integrates payment gateway and payment processor infrastructure for fintech, e-commerce, and retail businesses.
Technologies are important for conducting secure, efficient, and smooth transactions. Whether you are an online retailer, service provider, or brick-and-mortar store, choosing the right payment solution can significantly improve the customer experience and streamline your operations.
Understanding the difference between payment gateways and payment processors is important to make the right choice. This guide by Nimble AppGenie’s experts covers both concepts clearly with real examples and current industry data, so you know which one you need or whether you need both.
How Did We Get Here? A Short History of Digital Payments
Digital payments evolved from card-based transactions and electronic bank transfers into today’s mobile wallets, contactless payments, and real-time payment systems. Here’s a timeline of the key developments:
Late 1990s to Early 2000s: Emergence of Payment Gateways
- 1998: PayPal is founded, providing a new way to make payments online without sharing financial information directly with merchants.
- 1999: The term “payment gateway” starts to gain traction, describing technology that securely transmits payment information from customers to banks.
Early 2000s: Consolidation of Online Payments
- 2010: Stripe is founded by brothers Patrick and John Collison, focused on making it dramatically simpler for developers to integrate payment processing into websites.
Mid-to-Late 2000s: Smartphones and Mobile Payments
- 2007: The launch of the iPhone paved the way for mobile payments and the concept
- 2011: Google Wallet is introduced, allowing users to store credit card information on their smartphones and make payments using NFC (Near Field Communication) technology.
- 2014: Apple Pay was launched, further popularizing mobile payments and eWallets.
- 2015: Samsung Pay and Android Pay are launched, expanding the options for mobile payments.
- 2018: Google Wallet and Android Pay merge to form Google Pay, streamlining Google’s payment solutions.
2020s: The Future of Digital Payments
- 2020: The pandemic accelerated the adoption of digital payments, highlighting the importance of contactless transactions.
- 2023: The rise of cryptocurrency payments and blockchain technology introduces new possibilities for secure and decentralized transactions.
- 2025: Contactless payments and peer-to-peer payment solutions help in simplifying digital transactions without compromising time or solutions.
What Is a Payment Gateway?
A payment gateway is a technology that facilitates the transfer of payment information from a customer to a merchant’s bank account. It acts as an intermediary between the financial institution and merchant involved, ensuring sensitive payment data is securely transmitted and processed.
Payment gateway integration is essential for online transactions, providing the infrastructure needed to authorize payments and manage funds transfer. This layer connects a payment gateway to a user’s eWallet – see what a digital wallet is and how it fits into this flow.
When a customer makes a purchase, the gateway validates the payment details, checks for available funds, and processes the transaction, then communicates approval or denial back to the customer and merchant.
Key Terms
- Acquiring Bank: The merchant’s bank, which receives funds on the merchant’s behalf.
- Authorization: The real-time check confirming funds are available and the transaction is approved.
- Issuing Bank: The customer’s bank, which issued their card and approves or declines the transaction.
- Settlement: The actual transfer of funds from the customer’s bank to the merchant’s account, which can happen separately from authorization.
Key Features
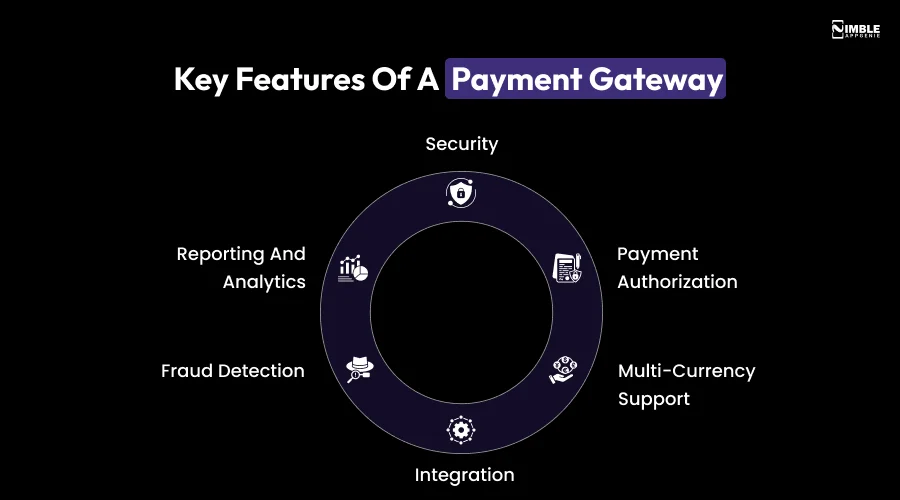
- Security: Payment gateways employ encryption and tokenization to protect sensitive payment information during transmission, reducing the risk of fraud.
- Payment Authorization: They validate payment information and authorize transactions in real-time, ensuring funds are available and the payment method is valid.
- Multi-Currency Support: Many gateways support multiple currencies, enabling international transactions and global commerce.
- Integration: Payment gateways can integrate with various e-commerce platforms, shopping carts, and point-of-sale systems, offering flexibility and ease of use.
- Fraud Detection: Advanced fraud detection tools and algorithms help identify and prevent fraudulent transactions, protecting both merchants and customers. Real-time fraud detection is increasingly AI-driven, read our guide on AI in digital payments to see how this works at the gateway level.
- Reporting and Analytics: They provide detailed reports and analytics, helping businesses monitor transactions, manage chargebacks, and gain insights into payment trends.
Who is it for?
Payment gateways are essential for:
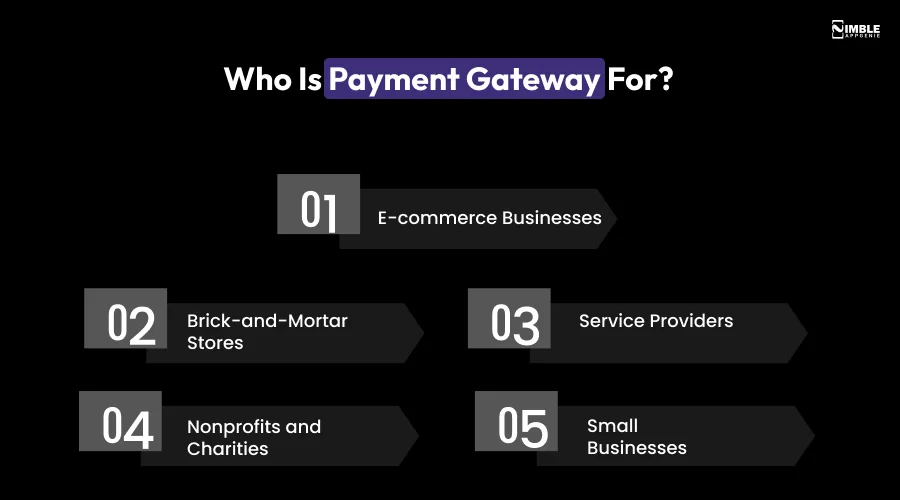
- E-commerce Businesses: Online retailers who need to securely process payments from customers worldwide.
- Brick-and-Mortar Stores: Physical stores that accept card payments and want to ensure secure transactions.
- Service Providers: Businesses offering online services, subscriptions, or digital products that require efficient payment processing.
- Nonprofits and Charities: Organizations that accept donations online and need a secure way to process these transactions.
- Small Businesses: Entrepreneurs and small businesses that sell products or services online and need a reliable payment processing solution.
Popular Examples
- PayPal: Known for security and ease of use, PayPal’s payment gateway is widely used across businesses of all sizes.
- Square: Square’s gateway supports online and in-person transactions, ideal for small and medium businesses.
- Stripe: A developer favorite, Stripe’s gateway offers robust APIs for mobile apps and websites.
- Adyen: Used by several large enterprises, with multi-currency support and advanced fraud prevention.
- Authorize.Net: A long-standing, reliable gateway supporting a wide range of payment methods and currencies.
What Is a Payment Processor?
A payment processor is a company that manages the technical aspects of processing debit and credit transactions – the intermediary between the merchant and the financial institutions involved. Merchants who want to accept payments via a single platform should also understand what a merchant service provider does, since it usually wraps around both the processor and gateway.
Processors ensure transaction data is securely transmitted from the merchant to the acquiring bank, then to the issuing bank for authorization, handling the communication and data transfer involved in authorization, clearing, and settlement.
Key Features
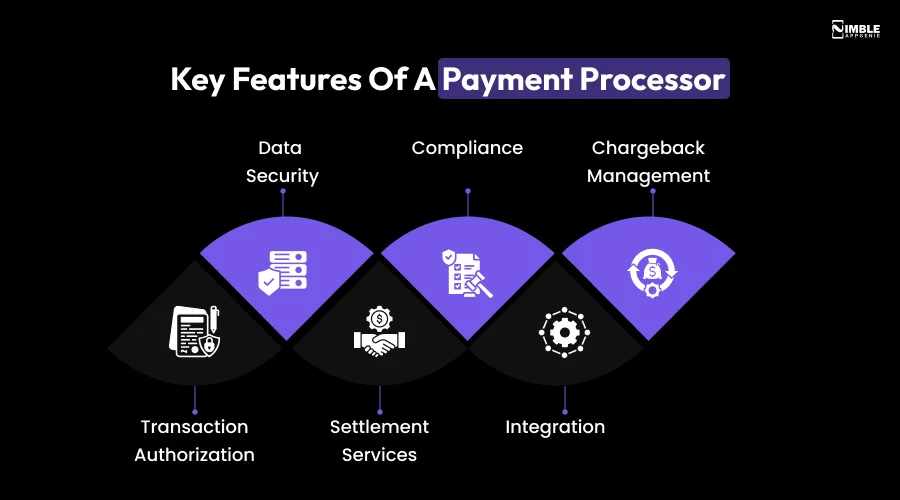
- Transaction Authorization: Verifying validity, checking for enough funds, and approving or declining based on the card issuer’s response.
- Data Security: Encryption and tokenization protect sensitive transaction data – see our guide on eWallet payment tokenization for how this works in transit.
- Settlement Services: Managing the transfer of funds from the customer’s account to the merchant’s account.
- Compliance: Ensuring compliance with PCI DSS and other industry standards.
- Integration: Connecting with POS systems, e-commerce platforms, and gateways.
- Chargeback Management: Helping merchants dispute fraudulent or erroneous transactions.
Who Is It For?
- E-commerce businesses requiring reliable card transaction handling.
- Service providers with subscriptions or recurring payments.
- Brick-and-mortar stores needing an efficient transaction processing system.
- Restaurants and hospitality businesses processing high transaction volumes quickly.
- Nonprofits and charities accepting card-based donations securely.
Popular Examples
- Fiserv: One of the largest processors, offering transaction authorization, settlement, and data security.
- Global Payments: Now the largest payment organization worldwide following its 2025 acquisition of Worldpay – the two are no longer separate competitors.
- Adyen: A global payment company with robust security and multi-currency support.
- Square: Known for versatility and ease of use across small and medium businesses, online and offline.
What’s the Difference Between a Payment Gateway and a Payment Processor?
Digital payments have revolutionized how businesses operate and how consumers make purchases.
To fully understand the landscape, it’s crucial to differentiate and understand the difference between payment gateways vs payment processors, as each serves a unique function within the digital payment ecosystem.
Here, we compare these three components across various parameters to provide a comprehensive understanding.
| Parameter | Payment Gateway | Payment Processor |
| 1. Definition | Technology for transmitting payment data | Company handling transaction processing |
| 2. Functionality | Authorizes and encrypts transactions | Manages communication and settlement |
| 3. Target Users | E-commerce businesses and online services | Retailers, service providers, non-profits |
| 4. Key Features | Real-time authorization and fraud detection | Transaction authorization and chargeback management |
| 5. Security | End-to-end encryption and tokenization | Secure data transmission and regular audits |
| 6. Cost | Transaction and setup fees | Transaction fees and additional charges |
| 7. Integration | E-commerce platforms and shopping carts | POS systems and e-commerce platforms |
| 8. Transaction Speed | Real-time authorization | Real-time authorization and settlement |
Here are some differences between a payment processor and a gateway. The idea of this distinction automatically gives you insights into making your decisions. However, even after you have understood the differences, you need to understand the solution.
How Big Is the Payment Processing Market?
This industry is large and consolidating fast, not just growing:
- The payments industry witnessed a major consolidation move when Global Payments completed its acquisition of Worldpay in January 2026. The combined company now serves 6+ million merchant locations and processes about $3.7 trillion in yearly payment volume across 175+ countries. (Source: Global Payments).
- Stripe processed $1.9 trillion in total payment volume in 2025, up 34% from $1.4 trillion in 2024. (Source: Stripe).
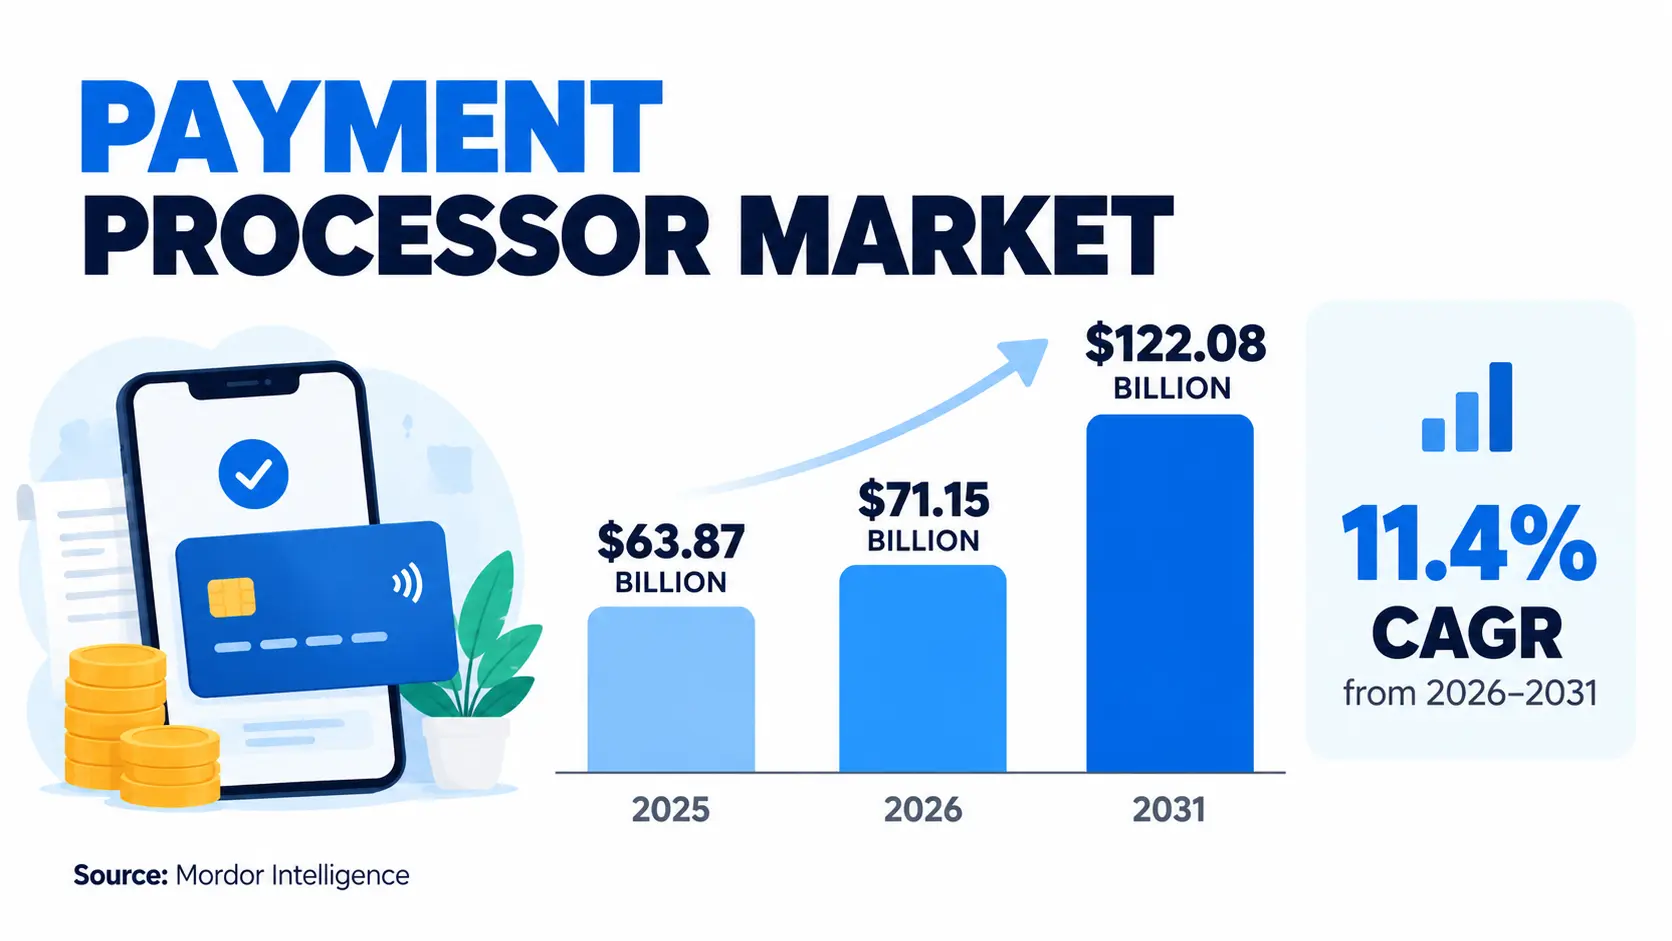
- The market was $63.87 billion in 2025, will reach $71.15 billion in 2026, and is projected to reach $122.08 billion by 2031, representing an 11.4% CAGR from 2026–2031. (Source: Mordor Intelligence).
- PayPal and Stripe together accounted for 64.36% of worldwide online payment-provider usage in January 2026, based on company website adoption. (Source: Statista, 2026.)
How Can Nimble AppGenie Help With Payment Gateway and Processor Development?
Nimble AppGenie develops payment solutions covering payment gateways, payment processors, and combined integrations, tailored to each client’s specific business requirements.
Nimble AppGenie has delivered 350+ payment solutions – gateway integrations, processor connections, and combined payment infrastructure – for fintech, e-commerce, and retail clients, verified on Clutch and GoodFirms. Every build starts from the client’s transaction volume and compliance requirements, not a standard template.
Conclusion
The practical distinction between a gateway and a processor is architectural: the gateway captures and encrypts payment data at the customer-facing layer; the processor routes it through the financial network and settles the funds.
Most businesses need both, and most modern providers (Stripe, Square, Adyen) deliver both under one integration – which is why the terminology is often used interchangeably, even though the functions are distinct.
Nimble AppGenie builds payment gateway integrations, custom processor connections, and combined payment infrastructure for fintech, e-commerce, and retail clients – scoped to transaction volume, compliance requirements, and platform architecture before development begins.
Start with the use case, and Nimble AppGenie will map the right gateway/processor configuration to it.
FAQs
A payment processor handles transaction authorization, clearing, and settlement, while a payment gateway securely transmits payment information. Nimble AppGenie can integrate both into your payment infrastructure.
Consider your business model, transaction volume, customer preferences, security needs, costs, and integration requirements. Nimble AppGenie can develop a solution around these requirements.
Look for encryption, tokenization, fraud detection, secure authentication, and PCI DSS compliance. Nimble AppGenie can incorporate these security measures into your payment solution.
Common costs include transaction, setup, monthly, chargeback, and currency-conversion fees. Nimble AppGenie can help you plan the required payment infrastructure and integrations.
Combining eWallets, gateways, and processors can support a smoother payment experience from checkout to settlement. Nimble AppGenie can integrate these components into a unified payment ecosystem.
Niketan Sharma, CTO, Nimble AppGenie, is a tech enthusiast with more than a decade of experience in delivering high-value solutions that allow a brand to penetrate the market easily. With a strong hold on mobile app development, he is actively working to help businesses identify the potential of digital transformation by sharing insightful statistics, guides & blogs.
Table of Contents



No Comments
Comments are closed.