Free Consultation
 PCI-DSS Compliant
 GDPR Ready
 ISO 27001
 NDA Protected
 AI Services
 AI App Development
 Generative AI Development
 AI Chatbot Development
 AI Integration Services
 AI For Fintech
 AI Financial Assistant Solution
 AI Insurance Agent Development
 Tech Stack
 OpenAI / GPT-4
 Claude / Anthropic
 Gemini / Google AI
 Llama / Open Source
 LangChain / LlamaIndex
 Pinecone / Pgvector
 AWS / Azure AI


 Fintech Solution
 Core Fintech
 Fintech App Development
 Neobank App Development
 eWallet App Development
 Payment Integration
 Lending Software
 BNPL Solution
 BNPL App Development
 Insurance App
 Investment App Dev
 Wealth Management App
 Crypto & DeFi
 DeFi App Development
 Crypto Wallet Dev
 Crypto Exchange Dev
 Trading Platform Dev
 Payments
 Compliance
 RegTech App Dev
 Fraud Detection
 Lending Ecosystem
 P2P Lending Platform
 Mortgage Lending
 Engagement
 Outsourcing Dev


 Mobile Development
 Mobile App Dev
 iOS App Development
 Android App Development
 React Native
 Flutter Development
 Web Development
 Node.js Development
 React.js Development
 Angular Development
 PHP / Laravel
 App Services
 UI/UX Design
 App Maintenance
 By Stage
 MVP Development
 Industry Solutions
 Healthcare App Dev
 Education App Dev
 Travel App Dev
 Real Estate App Dev
 Logistics Software
 Social Media App


 Hire Mobile Developers
 Hire iPhone Developers
 Hire Android Developers
 Hire React Native Devs
 Hire Flutter Developers
 Hire Web Developers
 Hire Node.js Developers
 Hire Angular Developers
 Hire PHP Developers
 Hire Laravel Developers
 How It Works
 Pre-Vetted Developers
 Ready In 48 Hours
 NDA From Day One
 Replace Guarantee

 Company
 About Us
 Portfolio
 Case Studies
 Blog / Insights
 Careers
 Contact Us
 Recognition


 Offices


Key Takeaways:
- P2P Lending is the model that offers a platform to connect individual investors directly with the borrowers.
- Microfinance is a service that provides small loans and insurance to low-income people and business owners who cannot use normal banks.
- In P2P lending vs microfinance, P2P lending connects borrowers with lenders, while in microfinance, you offer small loans to the low-income group.
- As a fintech startup, create your P2P lending app; here you should consider the target group of people, loan size, fund size, and your budget.
- Connect with a leading company such as Nimble AppGenie to create your own P2P lending app.
If you are a fintech enterprise or a startup looking to choose an investment model for your next software, app, or project, then you must look to P2P lending vs. microfinance; these two models are well researched and in trend due to rising interest rates in banks.
But one of the questions is: among P2P lending vs microfinance, which model is the most suitable to invest in?
Thus, to identify the right model, you should know the clear difference between P2P lending and microfinance.
In this guide, we will walk you through the meaning of both concepts and their key differences, and the reasons to connect with the leading engineers of Nimble AppGenie for a P2P lending app.
Without further ado, let’s begin.
What is P2P Lending?
P2P lending is a financial model that connects individual investors directly with the borrowers via online platforms. This is also known as social lending, offering an alternative way to access funds without involving traditional banks and financial institutions.
It is a method that is particularly advantageous for individuals with poor credit scores who struggle to secure funds via conventional channels.
This lending operates through dedicated online platforms that serve as a meeting place for lenders and borrowers.
The key points of P2P Lending:
- The maximum loan duration that is offered by a lender is 3 years.
- The total amount is capped at $5 million.
- A borrower cannot take a loan exceeding $1 million from all the P2P platforms combined.
- No single lender can extend more than $50K.
How Does P2P Lending Work?
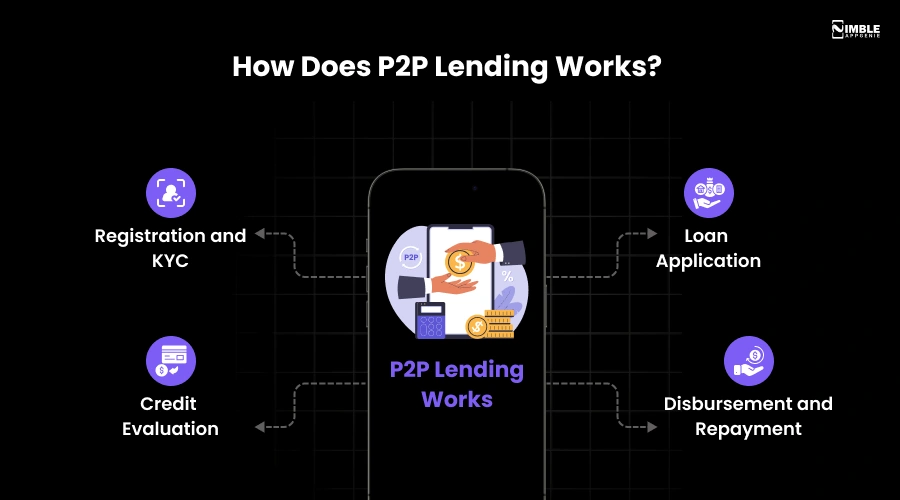
1. Registration and KYC
This is the first step, when both the borrowers and lenders sign up on a digital P2P lending platform by submitting the identity proofs, bank details, and completing the KYC checks.
2. Loan Application
The borrower should submit an application stating the required loan amount, tenure, and other information related to taking a loan.
3. Credit Evaluation
The platform evaluates the application’s credit history and financial data using the data models to assign a risk grade and the appropriate interest rate.
4. Disbursement and Repayment
Now, the app should opt for disbursement and repayment of money. Here, the borrower should make fixed monthly EMI payments to the platform and then distribute the principal and interest proportionally back to the lenders.
Now, before you evaluate microfinance vs P2P lending, let’s understand the concept of microfinance in the next section.
What is Microfinance?
Microfinance is a banking service that offers small loans, savings, insurance, and financial training to low-income people who do not have access to regular banks. It helps poor individuals to start small businesses and build self-sufficiency.
The primary goal is to foster financial inclusion, promote self-sufficiency, and alleviate poverty by assisting marginalized groups in building sustainable livelihoods.
The key components of Microfinance are:
► Microcredit
Small, collateral-free loans granted to individuals or small groups to start and grow small businesses.
► Savings Accounts
Microsavings in microfinance are the small deposit accounts that allow low-income individuals to safely store tiny amounts of money without high fees or even keeping the minimum balance rules.
► Microinsurance
Microinsurance in microfinance is a specialized financial safety that targets low-income households in developing countries with inefficient insurance markets.
How Does Microfinance Work?
Microfinance offers small loans and even financial services to low-income individuals who lack access to traditional banking services. It uses group support instead of physical property as a guarantee so people can start small businesses and earn money.
Here’s how Microfinance works:
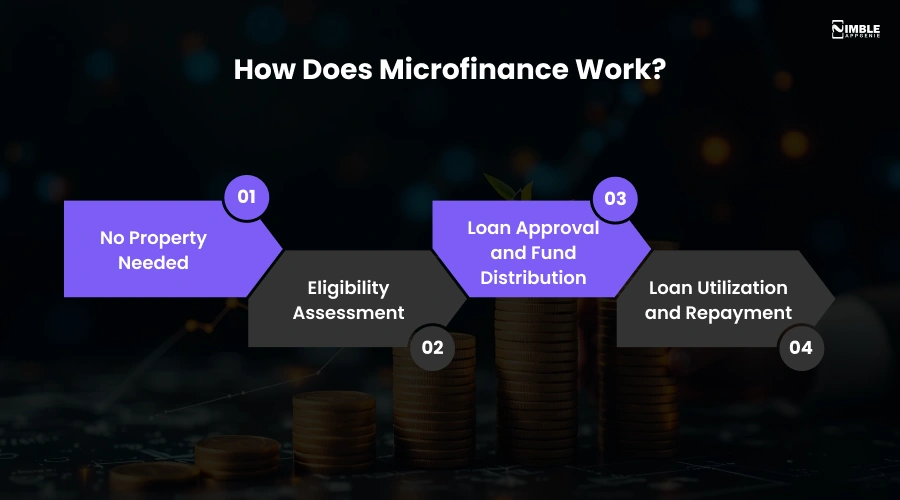
Step 1: No Property Needed
As collateral security, no property is required, unlike traditional banks, where collateral security is needed.
Step 2: Eligibility Assessment
Now, the complete eligibility assessment process is conducted to evaluate the household income limits, repayment capacity caps, and opting for the credit bureau checks.
Step 3: Loan Approval and Fund Distribution
The microfinance loan approval and fund distribution comprises eligibility screening, credit assessment, and direct fund disbursement.
Step 4: Loan Utilization and Repayment
Under this step, you can now opt for loan utilization and repayment. This step also covers how borrowed funds are spent, tracked, and paid back to a lender.
Now, after learning the details, many startups beginning within the industry often ask, “what the difference between P2P lending and microfinance is”?
One of the major differences you will note is in their structures. Let’s head on to the differences in the next section.
Bonus Read: How to Build a Loan Lending App?
Key Differences: P2P Lending Vs Microfinance
P2P lending is the finance model that connects individual borrowers and lenders; however, microfinance can be termed as financial services who offers basic banking and financial services such as small loans, savings accounts, and insurance to low-income individuals.
Here is the complete list of key differences between P2P lending vs microfinance:
| Parameter | P2P Lending | Microfinance |
| Definition | Online platform linking lenders & borrowers directly | Financial services for low-income individuals |
| Purpose | Alternative investment/borrowing option | Financial inclusion & poverty alleviation |
| Target Users | Individuals with varied credit profiles | Unbanked/underbanked, low-income groups |
| Fund Source | Retail/institutional investors | MFIs, NBFCs, NGOs, banks |
| Loan Size | Small to large | Very small (micro-loans) |
| Interest Rates | Market/risk-based | Often regulated or subsidized |
| Collateral | Usually unsecured | Unsecured; group guarantee model |
| Credit Check | Data/algorithm-driven | Trust & group-based assessment |
| Regulation | NBFC-P2P/fintech norms | NBFC-MFI/microfinance laws |
| Platform | Fully digital | Digital or field-agent based |
| Repayment | Flexible EMIs | Weekly/monthly, group-based |
| Lender Risk | Borne by individual lender | Shared via group liability |
| Focus | Profit-driven | Social impact-driven |
| Loan Use | Personal/business loans | Income-generating activities |
| Reach | Urban, tech-savvy | Rural, semi-urban |
Let’s have a detail on P2P lending vs microfinance:
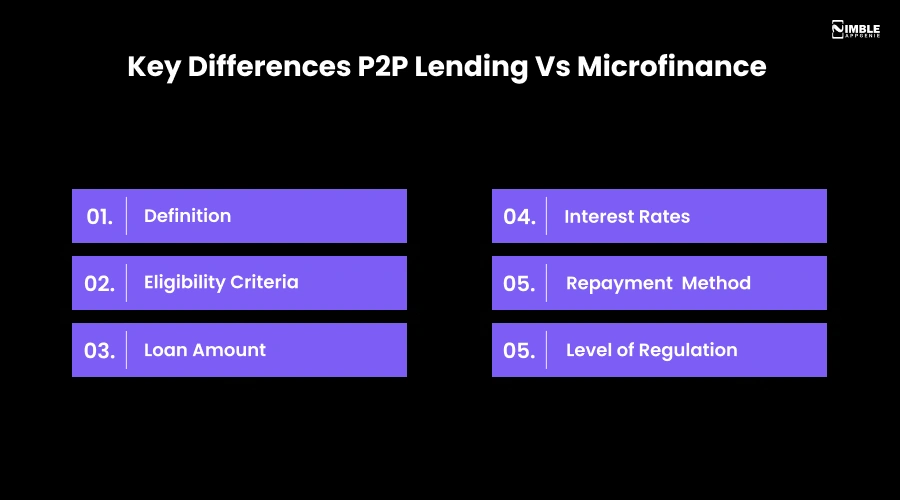
1. Definition
P2P Lending: P2P lending is a finance model that is also known as social lending and is a complete way to access funds without involving traditional banks and financial institutions. It is a platform that links borrowers and lenders.
Microfinance: Microfinance is the complete provision of offering financial services for low-income individuals.
2. Eligibility Criteria
P2P lending: Here, any person with a good credit score and steady income can participate. Here, people possess a stable income or a bank account with basic KYC verification.
Microfinance: Here, people with low-income groups, self-employed workers, or a joint liability group with an annual income of up to $300K are eligible.
3. Loan Amount
P2P Lending: It allows borrowers to request higher loan amounts depending on their creditworthiness.
Microfinance: Typically, the smaller loan amounts are suited for entrepreneurial ventures or income generation groups.
4. Interest Rates
P2P Lending: Offers competitive interest rates as borrowers negotiate directly with the individual lenders.
Microfinance: Microfinance interest rates typically range from 18% to 26% per annum, that is varied by lender and loan size.
5. Repayment Method
P2P Lending: Under this method, the primary repayment option is the Equated Monthly Instalment (EMI) model, where the borrowers pay back loans in scheduled instalments.
Microfinance: Here, the repayment period is shorter to support quick loan turnover.
6. Level of Regulation
P2P Lending: Governed by Guidelines issued by the government of the particular region; for example, if you’re operating in the US, you need to follow the P2P guidelines issued by that region. In the UK, you need to follow the P2P guidelines of that particular country.
Microfinance: The microfinances are regulated by the central banks, financial authorities, and even by the district government departments, completely dependent on the country.
Well, if you are confused about P2P lending vs microfinance, you are not alone.
Many fintech startups and tech firms often ask, “Which model to build: P2P lending vs Microfinance?”
Which Model to Build: P2P Lending vs Microfinance
P2P lending is the most convenient and suitable model for fintech startups and enterprises because here you operate purely as a fintech digital marketplace catering to the diversified needs of the borrowers and the lenders.
Here you can scale fast with low capital requirements, and the key advantages comprise utilizing the investor’s funds rather than your own balance sheet.
In P2P lending, you create a complete platform where the investor meets the borrower, while in microfinance, you need to use your own funds to give loans to small and low-income group people.
Different points you need to consider to select the P2P Lending model:
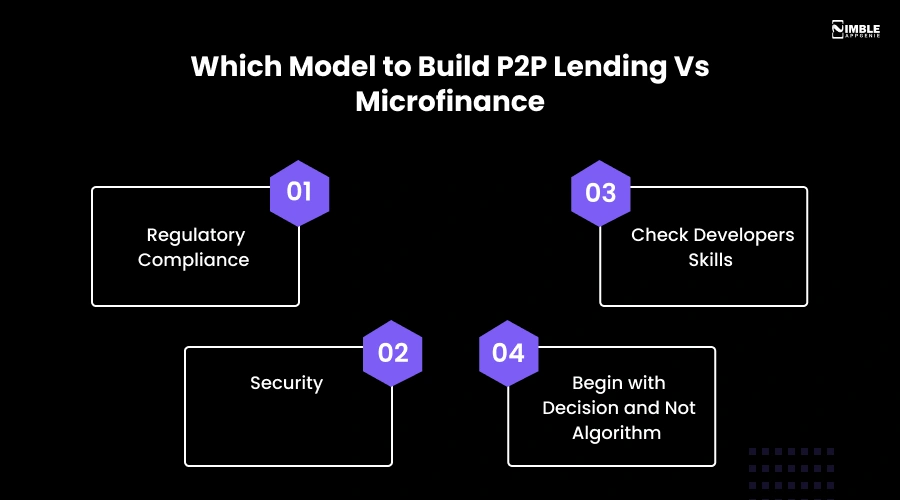
♦ Regulatory Compliance
You need to decide the geographical location and area, which will help determine the regulatory compliance. Implement the digital payment regulations and compliance as per the region to ensure that users get maximum benefits and your software remains sustainable.
For a P2P lending platform, success depends on balancing the legal mandates with user trust and seamless functionality for both the borrowers and the lenders.
♦ Security
Mobile app security is the prime factor to consider when you opt for building a P2P lending platform. In finance apps, you should consider end-to-end encryption and robust security models, multi-layered verification, and strict data protection.
Here, you need to implement access control, cryptographic protection, and trust-based validation.
♦ Check Developers Skills
You need to connect with experienced and niche fintech developers such as the engineers of Nimble AppGenie. Check the skills by starting with a short-term project. You can check their accessibility, skills on the project, and on-time delivery.
To build a P2P lending app, you need to check the availability of developers with technical proficiency, such as creating server logic using Node.js, Python, and Java, for handling matching algorithms.
♦ Begin With Decision and Not Algorithm
You need to begin with the type of business decision you want to improve, not the algorithm. Here, the highest value models are the ones that reduce risk and increase approvals for good borrowers, and enhance collections.
When adding AI to a P2P lending app, you should design your business logic around human and financial decisions before writing a single line of algorithmic code.
To create a well-engaged P2P lending app, you need to hire mobile app developers.
Why Partner With Nimble AppGenie to Build Your Model?
Nimble AppGenie is the best P2P Lending Platform Development Company due to its focus on security, regulatory compliance, and high retention rates of the clients. The engineers at Nimble AppGenie build different borrower features such as digital loan application, AI credit scoring, loan offer comparison, and many other investor features.
At Nimble AppGenie, the engineers develop diversified P2P lending solutions such as a mortgage P2P platform, a student loan P2P platform, and crypto-collateralized P2P lending.
Here are the different reasons to consider connecting with Nimble AppGenie:
➤ Competitive Pricing and Value For Cost
Connecting with Nimble AppGenie ensures that you get a competitive price based on the demands of the market. The management of Nimble AppGenie offers affordable hourly rates as per clients’ preferences.
➤ On-Time Delivery
The developers at Nimble AppGenie offer on-time delivery of projects along with transparency at every stage of the development process.
➤ Niche in Fintech
Nimble AppGenie has a niche in fintech apps; thus, the developers are effective in constructing P2P apps driving engagement.
➤ Extensive Track Record
Nimble AppGenie has delivered 350+ apps in the fintech and other categories, which makes us the leading experienced software development company.
Conclusion
P2P lending app is a platform where lenders and borrowers meet; however, microfinancing is the act of offering small loans and financial services to low-income groups who do not have access to traditional banks.
In the case of a P2P lending app and microfinance, the businesses should opt for the P2P lending model because here they can connect the borrowers with the lenders, while in microfinancing, you offer funds to low-income groups.
To decide which model to build, you should evaluate different parameters such as budget, project objectives, and security parameters. Here, connecting with a well-reputed company can be helpful.
FAQs
Niketan Sharma, CTO, Nimble AppGenie, is a tech enthusiast with more than a decade of experience in delivering high-value solutions that allow a brand to penetrate the market easily. With a strong hold on mobile app development, he is actively working to help businesses identify the potential of digital transformation by sharing insightful statistics, guides & blogs.