Free Consultation
 PCI-DSS Compliant
 GDPR Ready
 ISO 27001
 NDA Protected
 AI Services
 AI App Development
 Generative AI Development
 AI Chatbot Development
 AI Integration Services
 AI For Fintech
 AI Financial Assistant Solution
 AI Insurance Agent Development
 Tech Stack
 OpenAI / GPT-4
 Claude / Anthropic
 Gemini / Google AI
 Llama / Open Source
 LangChain / LlamaIndex
 Pinecone / Pgvector
 AWS / Azure AI


 Fintech Solution
 Core Fintech
 Fintech App Development
 Neobank App Development
 eWallet App Development
 Payment Integration
 Lending Software
 BNPL Solution
 BNPL App Development
 Insurance App
 Investment App Dev
 Wealth Management App
 Crypto & DeFi
 DeFi App Development
 Crypto Wallet Dev
 Crypto Exchange Dev
 Trading Platform Dev
 Payments
 Compliance
 RegTech App Dev
 Fraud Detection
 Lending Ecosystem
 P2P Lending Platform
 Mortgage Lending
 Engagement
 Outsourcing Dev


 Mobile Development
 Mobile App Dev
 iOS App Development
 Android App Development
 React Native
 Flutter Development
 Web Development
 Node.js Development
 React.js Development
 Angular Development
 PHP / Laravel
 App Services
 UI/UX Design
 App Maintenance
 By Stage
 MVP Development
 Industry Solutions
 Healthcare App Dev
 Education App Dev
 Travel App Dev
 Real Estate App Dev
 Logistics Software
 Social Media App


 Hire Mobile Developers
 Hire iPhone Developers
 Hire Android Developers
 Hire React Native Devs
 Hire Flutter Developers
 Hire Web Developers
 Hire Node.js Developers
 Hire Angular Developers
 Hire PHP Developers
 Hire Laravel Developers
 How It Works
 Pre-Vetted Developers
 Ready In 48 Hours
 NDA From Day One
 Replace Guarantee

 Company
 About Us
 Portfolio
 Case Studies
 Blog / Insights
 Careers
 Contact Us
 Recognition


 Offices


TL;Dr
Financial Conduct Authority (FCA) authorisation is essential for fintech startups that want to offer regulated financial services in the UK. The right route depends on your business model: e-money, payment services, or cryptoasset activities. Application timelines vary, and the FCA’s Q1 2026/27 operating metrics reported a median of 219 days for authorisation applications. Startups should plan for application fees, regulatory capital, safeguarding, governance, and ongoing compliance before applying.
- FCA authorisation is based on your business activities. Fintech startups should identify whether their services fall under the Financial Services and Markets Act 2000, the Electronic Money Regulations 2011, the Payment Services Regulations 2017, or the upcoming cryptoasset regulatory framework.
- Payment institutions and e-money institutions follow distinct regulatory routes. Payment institutions are usually regulated under the Payment Services Regulations 2017, while e-money institutions fall under the Electronic Money Regulations 2011.
- FCA application fees depend on the type of authorisation. The applicable fee varies based on regulatory category and application type. Check the FCA’s latest application fee schedule before preparing your application.
- Regulatory capital requirements differ by licence type. Authorised e-money institutions usually need initial capital of about €350,000. Payment institutions have distinct capital requirements depending on the payment service they offer, as set out in Schedule 3 of the Payment Services Regulations 2017.
- Application timelines depend on complexity and completeness. The FCA states that complete payment institution and e-money institution applications are assessed within three months, while incomplete applications can take up to 12 months. Actual timelines can differ, as shown in the FCA’s authorisation service metrics.
- Safeguarding and record-keeping continue after authorisation. Payment and e-money firms should maintain appropriate safeguarding arrangements and meet applicable reconciliation and record-keeping requirements under CASS 15.
FCA authorisation is permission from the Financial Conduct Authority to carry on regulated financial activities in the UK. You need it if your startup provides payment services, issues e-money, arranges investments, or lends to consumers; from October 2027, offers cryptoasset services, unless a partner model or exclusion applies.
This guide helps CTOs and non-technical founders choose a route, estimate costs and timelines, and understand what the platform should do. It separates statutory deadlines from real outcomes.
Do You Need FCA Authorisation?
Yes, if you carry on a regulated activity by way of business in the UK and no exclusion applies. The law lists regulated activities, so the test is what your platform does with credit, money, cryptoassets, or investments, not how you describe your business. Serving UK customers from abroad can also bring you within scope.
Three layers apply. The Financial Services and Markets Act 2000 (FSMA 2000) restricts regulated activities without permission; Part 4A of FSMA 2000 grants that permission for credit, investments and, soon, crypto.
Payments and e-money sit under the Payment Services Regulations 2017 (PSRs 2017) and the Electronic Money Regulations 2011 (EMRs 2011). Financial promotions are also controlled, so you can’t market a regulated product unless an authorised firm approves it.
A remittance app offers payment services, and a wallet that stores balances issues e-money. An invoice finance platform may sit outside consumer credit rules if it lends only to companies, but sole traders can change that.
Taking deposits is a different regime. If you are planning a neobank, our guide to full banking licences covers that route.
Which FCA Permission Does Your Fintech Need?
The permission follows your business model. Holding customer balances points to e-money; moving money for others points to payment services; arranging investments points to Part 4A permissions; and lending points to consumer credit. Under the new regime, crypto services need FSMA authorisation; the table maps common models to routes.
| Business model | Permission needed | Route | Key requirement | Notes |
| Wallet or prepaid card | E-money issuance | Authorised e-money institution (EMI); small EMI if average outstanding e-money stays within €5 million | €350,000 initial capital (authorised) | Safeguarding applies |
| Remittance app | Money remittance | Authorised payment institution (API); small payment institution if monthly payments average within €3 million | €20,000 initial capital | Safeguarding applies |
| Merchant acquiring or payment accounts | Core payment services | Authorised payment institution | €125,000 initial capital | Card and wallet flows in scope |
| Pay-by-bank | Payment initiation | Authorised payment institution | €50,000 initial capital | Outside the new safeguarding rules |
| Data dashboard | Account information | Registered account information service provider (RAISP) | No initial capital; insurance or comparable guarantee | Fee £1,130 |
| Lending app or buy now pay later | Consumer credit; buy now pay later regulated from 15 July 2026 | Part 4A, limited or full permission | Affordability checks; Consumer Duty (FCA rules on good outcomes for retail customers) | Temporary permissions regime: firms must still seek full authorisation] |
| Investment or advice app | Part 4A investment permissions | Authorised firm or appointed representative | Senior Managers and Certification Regime (SM&CR) | Capital varies |
| Crypto exchange or custody | Money laundering registration today; FSMA authorisation from 25 October 2027 | Gateway open to 28 February 2027 | AML controls; new prudential regime | No automatic conversion |
If X, then Y:
- You hold customer balances: plan for an authorised EMI, or a small one under the limit.
- You move money between parties: use a payment institution for small amounts below €3 million.
- You only read bank data: register as an account information provider.
- You lend to individuals: seek consumer credit permission; marketplace models meet extra lending platform rules.
- You arrange or manage investments: seek Part 4A permissions or an appointed representative arrangement.
- You offer crypto services: plan for FSMA authorisation, not registration alone.
FCA Authorisation Routes Compared
EMI and payment institution routes carry the heaviest payment obligations; small registrations are lighter but capped, and credit, investment and crypto routes stay under different FCA rules. The table compares what each route allows: safeguarding, complexity, and capital. Complexity ratings are our experience-based view, not FCA classifications.
| Route | What you can do | What you cannot do | Safeguarding | Capital | Complexity |
| Authorised EMI (the “FCA EMI licence” founders search for) | Issue e-money; provide payment services | Lend or take deposits | Yes | €350,000 | High |
| Authorised payment institution | Provide chosen payment services | Issue e-money | Yes, except payment-initiation-only or account-information-only firms | €20,000, €50,000 or €125,000 by service | Medium to high |
| Small payment institution / small EMI | Operate within limits | Exceed €3 million monthly payments or €5 million e-money | Small EMI yes; small payment opt-in | Small payment: none. Small EMI: none below €500,000 average e-money, then 2% | Lower to medium |
| RAISP | Access account data with consent | Initiate payments or hold funds | Not applicable | None; insurance or guarantee | Lower |
| Consumer credit | Lend or broker credit to individuals | Take deposits | Not applicable | No universal fixed minimum; adequate financial resources required, with additional prudential requirements depending on activities. | Medium |
| Part 4A investments | Arrange, deal in or manage investments | Anything outside permissions | Client asset rules if holding assets | £75,000, £150,000, £750,000 or £4 million, depending on firm type and permissions; additional own-funds requirements may apply. | High |
| Crypto | Operate under registration now; regulated activities from 25 October 2027 with authorisation. | Continue after that date without it | New custody rules | Registration: none. Authorisation: £75,000–£750,000 permanent minimum, depending on activity; higher own-funds requirements may apply. | High |
The FCA Authorisation Process, Step by Step
The FCA authorisation process runs from perimeter analysis to a decision, and your preparation largely decides how long it takes. You submit through Connect, the FCA’s online application system, with a business plan, governance, projections, safeguarding, and anti-money laundering evidence. The FCA then asks questions until the application is completed. These steps cover the usual FCA authorisation requirements.
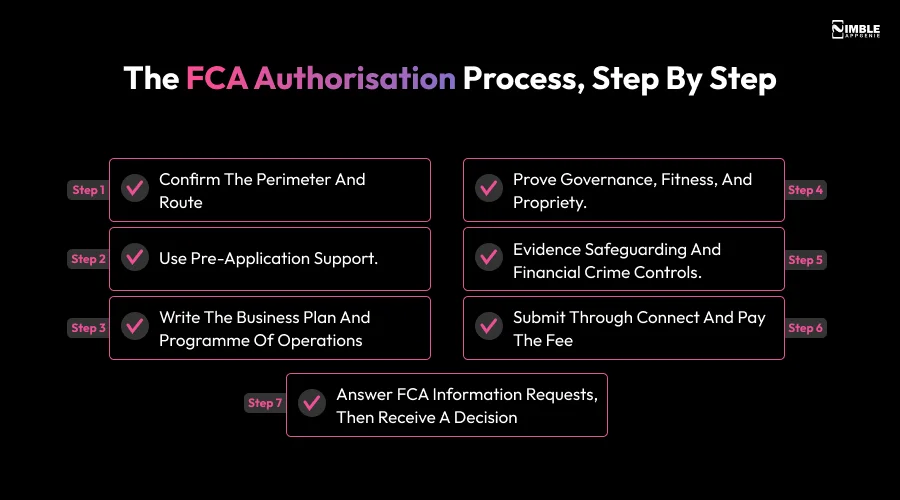
- Confirm the perimeter and route. Get written advice on which permission fits.
- Use pre-application support. The FCA’s free pre-application support service (PASS) is open to payment, e-money, and crypto applicants; it offers no advice or guarantee. The FCA regulatory sandbox suits novel propositions but is no shortcut.
- Write the business plan and programme of operations. Explain customers, projections, money flows, and a wind-down plan. Prove governance, fitness, and propriety. Controllers, directors, and responsible persons are assessed; FSMA firms also name SM&CR roles.
- Evidence safeguarding and financial crime controls. Policies should fit working systems, with a credible money laundering reporting officer.
- Submit through Connect and pay the fee: It’s non-refundable.
- Answer FCA information requests, then receive a decision. If refused, the FCA’s refusal process applies.
How Long Does FCA Authorisation Take?
By law, the FCA has three months to decide a complete payments or e-money application and up to 12 months if it’s incomplete. In practice, the FCA’s published median for April to June 2026 was 219 days. Treat statutory deadlines as legal limits and observed medians as planning guides, not commitments.
| Application type | Statutory deadline (complete/incomplete) | FCA service standard | Observed median, April to June 2026 |
| Payments and e-money | 3 months / 12 months | 3 months / 10 months | 219 days (quartiles 168 to 268) |
| New firm, Part 4A, all sectors | 6 / 12 months today; 4 / 10 confirmed, pending legislation | 4 months / 10 months | 131 days (91 to 190) |
| Credit and lending (limited/other) | As above | As above | 108 / 124 days |
| Consumer investments | As above | As above | 285 days |
| Crypto registration (money laundering rules) | Not applicable | 3 months, complete applications | 236 days (120 to 297) |
| Crypto FSMA authorisation | Not applicable | Decision before 25 October 2027 if you apply by 28 February 2027 | Not yet available |
These medians are observed results, not FCA commitments, and incomplete applications take longer. Preparation before submission is extra.
Download the FCA Authorisation Readiness Checklist to test your application before you submit.
How Much Does FCA Authorisation Cost?
The FCA application fee is only one cost line. As of November 2026, it runs from £1,130 to £5,640 for payments and e-money firms and is non-refundable. Regulatory capital, compliance staff, technology, legal advice, and ongoing fees add to it, so budget for all six lines below.
| Cost line | Figure (as of November 2026) |
| FCA application fee | Small payment institution, small EMI, RAISP: £1,130. Authorised payment institution: £2,820 (remittance, payment initiation or account information only) or £5,640. Authorised EMI: £5,640. Consumer credit: £560 (limited) or £1,130, £5,640 or £11,260 (full). Investments: £2,820 for most intermediaries, £11,260 for most investment managers. Crypto registration: £11,260 |
| Regulatory capital | €350,000 (authorised EMI); €20,000, €50,000 or €125,000 (authorised payment institution); none for RAISP. Capital is held, not spent |
| Legal and advisory | Approximately £5,000–£45,000+, depending on application type, complexity and advisory scope. VAT and third-party costs may be additional. |
| Compliance staffing | Approximately £50,000–£90,000 for a Compliance Officer and £75,000–£120,000 for an MLRO annually. Combined roles may cost £80,000–£130,000. |
| Technology and compliance systems | Variable; depends on business model, transaction volumes, integrations, security requirements and third-party providers. Nimble estimate subject to discovery. |
| Ongoing FCA fees | 2026/27: Small payment institution £652; small EMI £1,432; authorised payment institution and RAISP £628 minimum plus variable charges; authorised EMI £628 minimum for payment services and £2,063 minimum for e-money issuance, plus applicable variable charges. Other routes have separate fee blocks. |
What the FCA Expects From Your Product and Technology
The FCA partly judges your application on whether your platform can confirm it protects customer money and manages risk. Safeguarding records, reconciliation, incident reporting, audit trails, data protection, resilience, and strong customer authentication should be designed in, not added later. Each requirement below demonstrates what it means for the build.
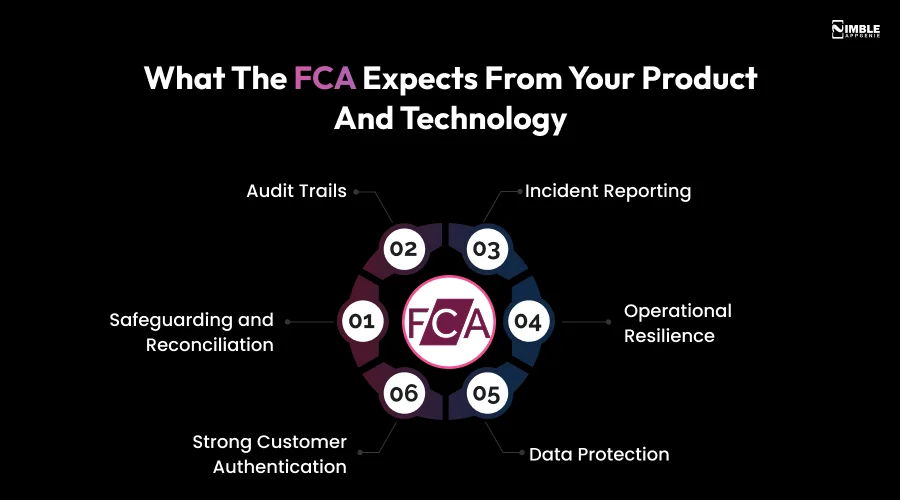
1. Safeguarding and Reconciliation
From 7 May 2026, new UK safeguarding requirements apply to authorised payment institutions (except payment-initiation-only or account-information-only firms) and authorised and small EMIs; small payment institutions may opt in under the FCA safeguarding rules. Expect internal and external reconciliation at least once every reconciliation day under CASS 15, a resolution pack, a monthly return within 15 business days of month-end, and an annual audit, unless exempt. The audit exemption applies if the firm has not been required to safeguard more than £100,000 at any time over at least 53 weeks, as explained in the FCA’s policy statement. Build segregated ledgers, automated reconciliation with exception queues, and exportable records.
2. Audit Trails
Books and records should be accurate and retrievable. Build append-only logs of payments, balance changes, admin actions, and access. Customer checks belong in the same trail; see KYC and AML compliance for fintech.
3. Incident Reporting
From 18 March 2027, FCA rules require payment service providers and Part 4A firms to report operational incidents through Connect. Build detection, severity classification, and a workflow that captures timelines and root cause.
4. Operational Resilience
Map critical services, test recovery, and track third-party dependencies. From 18 March 2027, authorised payment institutions and authorised EMIs should report material third-party arrangements under PS26/2.
5. Data Protection
UK GDPR applies. Accumulate only what you need, encrypt data, limit access, and set retention rules.
6. Strong Customer Authentication
The PSRs 2017, Regulation 100, require strong customer authentication when users access payment accounts online, perform certain risky remote actions, or initiate electronic payments, subject to specific exemptions. Build two-factor authentication, exemption logic, and fraud monitoring.
Common Reasons Applications Are Delayed or Refused
Delays usually start with incomplete and unconvincing applications. An application is complete only when the FCA holds everything it needs, and the 12-month limit applies. These eight issues commonly slow or sink applications, and you can fix them before submission.
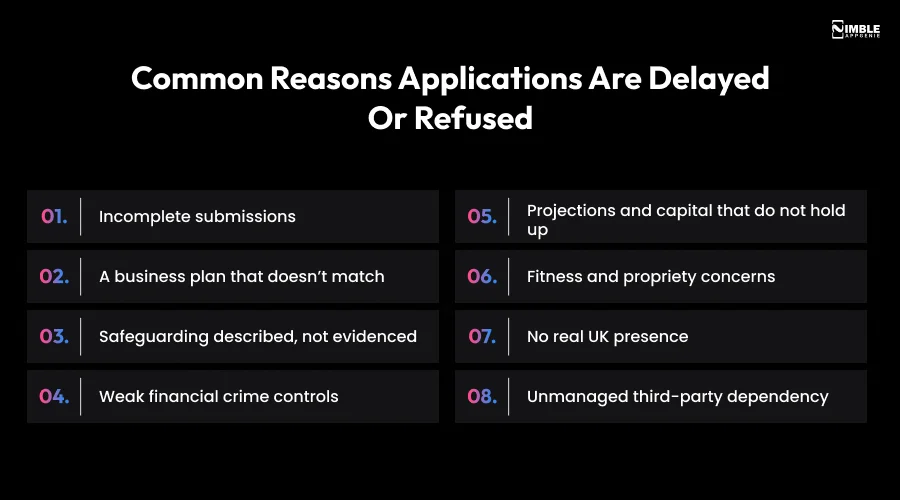
- Incomplete submissions that compel the FCA to chase evidence.
- A business plan that doesn’t match how the platform moves money.
- Safeguarding described, not evidenced, against the rules in force since 7 May 2026.
- Weak financial crime controls or an under-resourced MLRO.
- Projections and capital that do not hold up, or no wind-down plan.
- Fitness and propriety concerns about directors, controllers or funding sources.
- No real UK presence: payment institutions need a UK head office.
- Unmanaged third-party dependency without oversight or exit plans.
Authorised Firm, Appointed Representative or Partner Model: Which Is Right?
Choose your authorisation for control, an appointed representative arrangement for FSMA activities such as investments, or a partner model for speed. Each option forces you to choose between freedom, time, and money. The right fit depends on whether the regulated activity is your core product, and whether a partner will accept the risk.
| Model | How it works | Fits when | Trade-off |
| Authorised firm | You hold the permission | Regulated activity is your core product | Cost, time, ongoing duties |
| Appointed representative | You act for an FSMA-authorised principal responsible for your regulated activities | Investments or credit broking with a willing principal | Principal sets limits; not for payment institution status |
| Agent or partner programme | You provide services under a payments or e-money firm’s authorisation | You want to launch and validate quickly | Partner controls limits and exit |
A partner doesn’t remove your own duties. See wider fintech compliance requirements before you decide.
How Nimble AppGenie Supports Your FCA Application
Nimble AppGenie builds the technology side of regulated fintech products. Authorisation is a legal and regulatory process that requires qualified advisers, and we don’t give legal advice or submit applications. We create the platform, controls, and documentation your adviser needs. Our fintech app development service covers:
- Compliance-ready architecture for your chosen permission.
- Audit logging for payments, balances, and admin actions.
- Safeguarding and reconciliation ledger with exception queues.
- KYC and AML integrations for onboarding and monitoring.
- Technical documentation for the application.
- Regulatory reporting for returns and incident reports.
Conclusion
FCA authorisation comes down to three things: choosing the right permission, submitting a complete application, and building a platform that proves its controls. Fees are modest, but capital, systems, and advice drive the real cost, and decisions take months, not weeks.
Your next step is to confirm your route with a regulatory lawyer, then scope the technology early so the application and the build stay aligned. Book a free fintech consultation, and we will map what the platform should do.
FAQs
These answers cover common founder questions about FCA authorisation, from timelines and costs to partner models. They reflect regulatory information as of 4 November 2026 and are general information, not legal advice, so confirm your position with a regulatory lawyer before you apply.
Niketan Sharma, CTO, Nimble AppGenie, is a tech enthusiast with more than a decade of experience in delivering high-value solutions that allow a brand to penetrate the market easily. With a strong hold on mobile app development, he is actively working to help businesses identify the potential of digital transformation by sharing insightful statistics, guides & blogs.